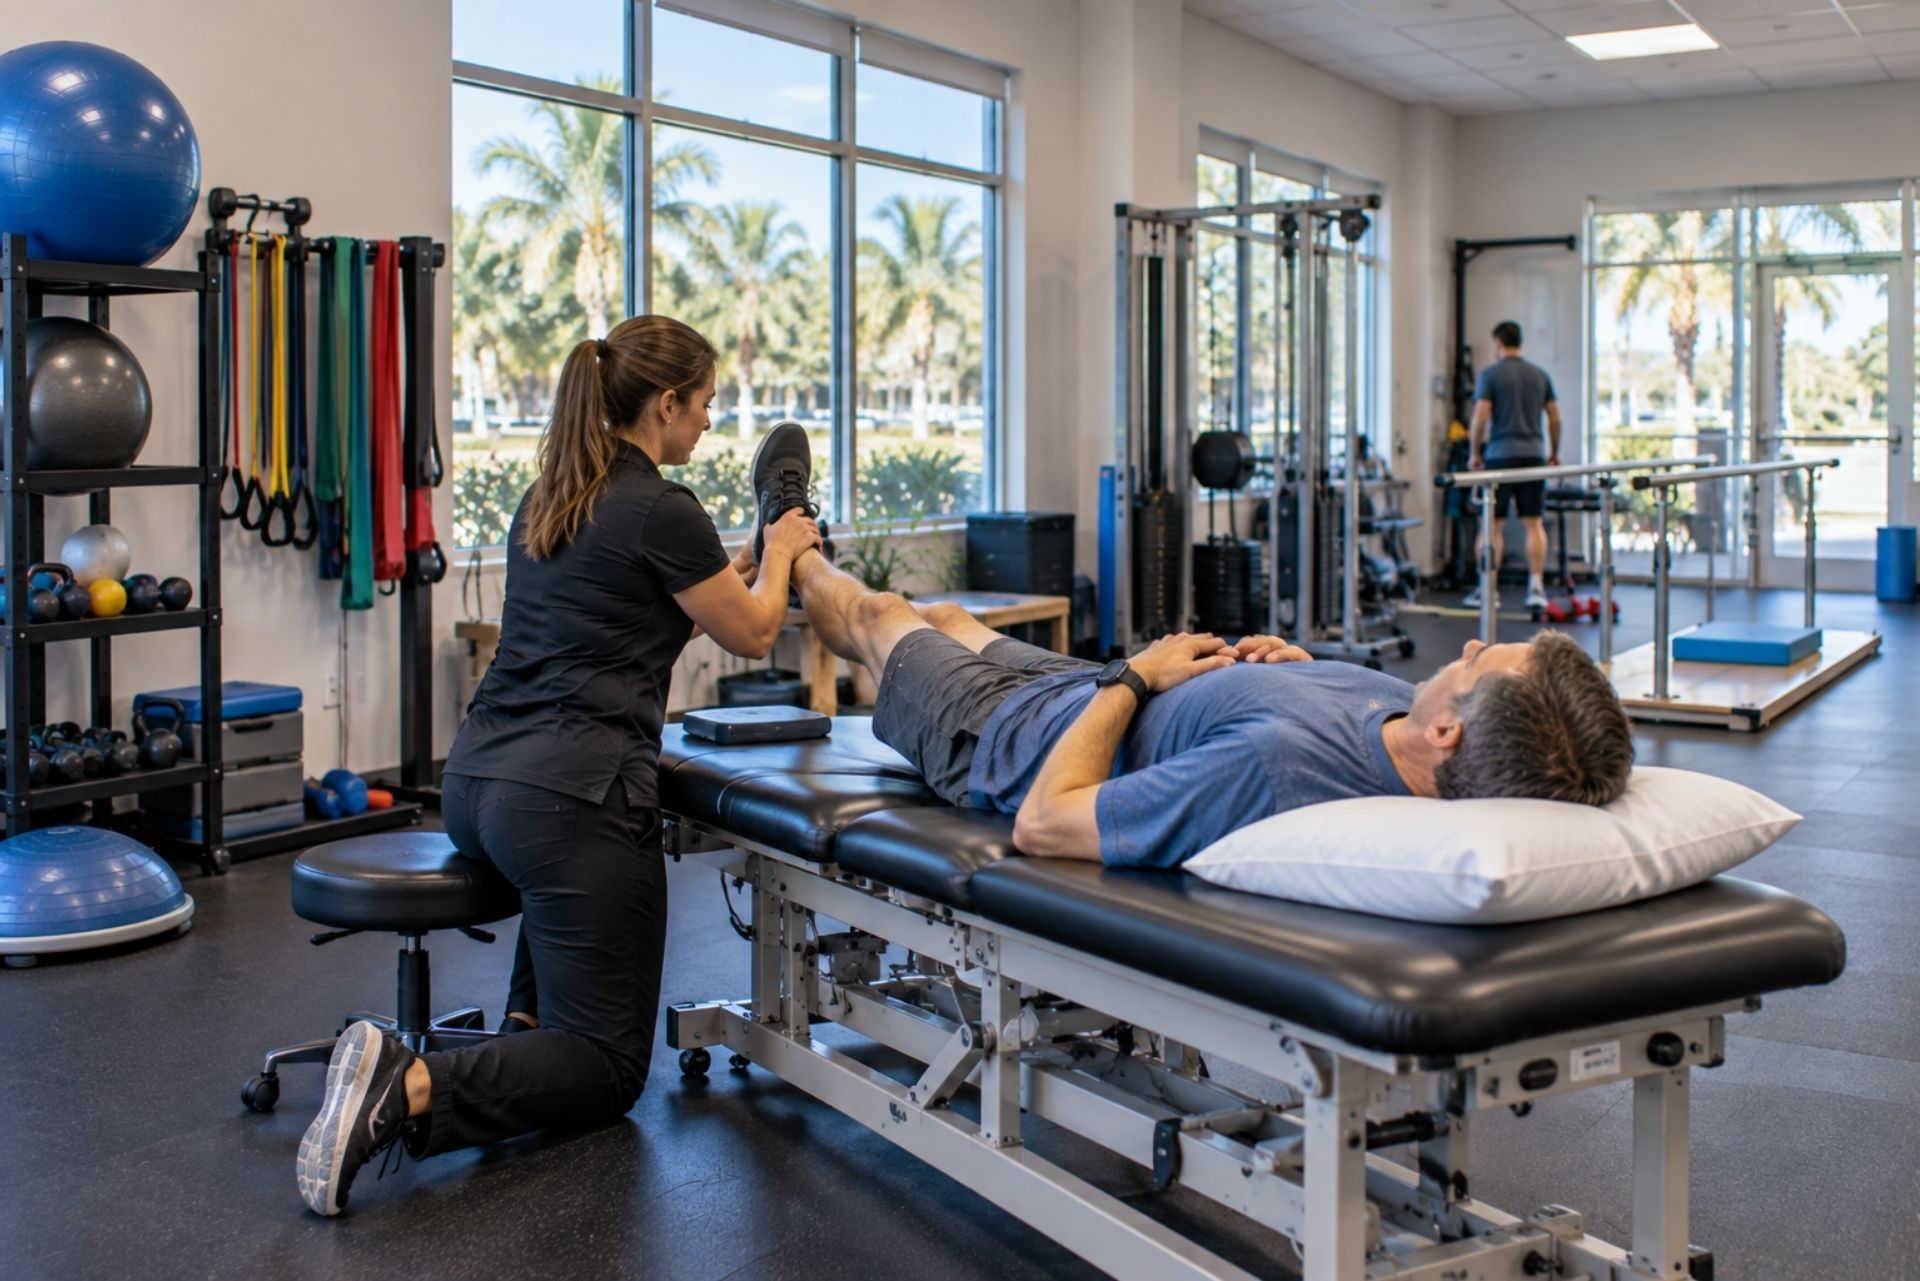
A single malpractice claim against a physical therapy practice can cost $50,000 or more before you even step into a courtroom. Pair that with Florida's hurricane exposure, its unique PIP auto insurance system, and rising cybersecurity threats targeting healthcare providers, and you've got a risk profile that generic business insurance simply won't cover. Physical therapy clinics in Florida face a distinct combination of clinical, environmental, and regulatory pressures that demand specialized coverage.
Whether you run a solo outpatient clinic in Tampa or a multi-location sports rehab group across South Florida, the right insurance package protects your livelihood, your staff, and your patients. Florida's PIP law remains in effect for 2026 after repeal bills SB 522 and HB 76 failed to pass, which means the state's no-fault auto insurance framework continues to shape how injury patients arrive at your door and how claims get processed. That regulatory reality directly affects your billing, your liability exposure, and the type of coverage you need.
This guide breaks down the specific policies, state mandates, and risk factors that matter most for PT clinic owners operating in the Sunshine State. You'll find practical details on coverage types, cost ranges, compliance requirements, and the digital threats that many
practice owners overlook until it's too late.
Essential Insurance Coverage for Florida Physical Therapy Clinics
Running a PT clinic means juggling clinical care, business operations, and patient safety all at once. Your insurance portfolio needs to reflect that complexity. A single policy won't cover the range of risks you face daily, from a patient alleging improper treatment to a hurricane damaging your clinic's hydrotherapy equipment.
Most Florida PT clinics need a layered approach : professional liability, general liability, and commercial property coverage working together. Each policy addresses a different category of risk, and gaps between them are where practice owners get caught. A tailored insurance program for physical therapy practices typically bundles these core coverages while allowing you to add endorsements for your specific situation.
Professional Liability and Malpractice Insurance
Professional liability, often called malpractice insurance, covers claims that arise from your clinical work. If a patient alleges that your treatment plan caused injury, worsened their condition, or deviated from accepted standards of care, this policy responds. Common claim triggers in PT include improper manual therapy techniques, failure to modify exercises for a patient's limitations, and inadequate documentation of treatment progress.
In Florida, malpractice claims against physical therapists tend to involve soft tissue injuries, falls during supervised exercise, and alleged negligence in post-surgical rehab protocols. Policies typically offer $1M per occurrence and $3M aggregate limits, though high-volume clinics or those treating complex orthopedic cases may want higher limits. Expect annual premiums between $1,200 and $4,000 per provider, depending on your claims history and patient volume.
General Liability for Patient Slip-and-Falls
General liability insurance covers bodily injury and property damage claims that aren't related to your professional services. The classic example : a patient slips on a wet floor in your lobby and breaks a wrist. That's not a malpractice claim. It's a premises liability claim, and your professional liability policy won't pay for it.
Florida's year-round rain and humidity create constant slip-and-fall hazards, especially in clinics with pool therapy areas or outdoor walkways. General liability also covers advertising injury claims and damage you cause to rented spaces. Most PT clinics carry $1M per occurrence with a $2M aggregate, and premiums typically run $500 to $2,500 annually for a single-location practice.
Commercial Property Coverage for Specialized Equipment
PT clinics house expensive, specialized equipment. A single Biodex isokinetic testing system can cost $30,000 or more, and a full clinic outfitting with treatment tables, ultrasound units, electrical stimulation devices, and exercise machines can easily exceed $150,000 in replacement value. Commercial property insurance covers this equipment against fire, theft, vandalism, and certain weather events.
Florida's hurricane season adds a critical wrinkle. Standard commercial property policies often exclude wind and flood damage, or they carry separate, higher deductibles for named storms. Clinics in coastal areas like Brickell, Fort Lauderdale, or the Gulf Coast need to verify their wind and flood coverage carefully. A Category 2 storm can destroy equipment, damage your building, and shut your practice down for weeks, so business interruption coverage is worth adding to your property policy.
By: Montreal Morand
Founder & Managing Partner
Macpherson Insurance Agency
Florida State Requirements and Legal Mandates
Florida imposes specific insurance and regulatory requirements on PT clinic owners that go beyond what you'd find in many other states. Ignoring these mandates can result in fines, license suspension, or personal liability exposure.
Workers' Compensation Laws for Small Practices
Florida law requires workers' compensation coverage for businesses with four or more employees, including part-time staff. Construction-related businesses face a stricter threshold of just one employee, but PT clinics fall under the general rule. Even if you have only three employees, carrying workers' comp is smart risk management, because a single workplace injury claim from an uninsured employee can result in a lawsuit against you personally.
The state's workers' compensation requirements for 2026 include penalties for non-compliance that can reach $1,000 per day. Corporate officers can exempt themselves from coverage, but this exemption has limits and doesn't protect you from employee claims. Premiums for PT clinics vary based on your payroll size and claims experience, but expect to pay between $0.80 and $2.50 per $100 of payroll.
Florida Board of Physical Therapy Regulations
The Florida Board of Physical Therapy Practice, operating under the Department of Health, sets licensure and practice standards that directly affect your insurance needs. All licensed PTs must maintain an active license, and clinics must register as healthcare entities. The board doesn't mandate specific insurance minimums for PTs the way it does for physicians, but operating without professional liability coverage exposes your personal assets to any malpractice judgment.
Florida's
PIP 14-day rule still applies in 2026, requiring auto accident victims to seek treatment within 14 days to qualify for PIP benefits. This rule drives a significant portion of patient volume to PT clinics, particularly for whiplash and soft tissue injuries. Your billing practices around PIP claims need to be airtight, because improper PIP billing can trigger fraud investigations and insurance disputes that your professional liability policy may not fully cover.
Comparing Primary Policy Types
Understanding the difference between your two foundational policies prevents confusion during a claim. Too many clinic owners assume their general liability covers everything, only to discover the gap when a patient files a malpractice complaint.
Table: Professional Liability vs. General Liability
| Feature | Professional Liability | General Liability |
|---|---|---|
| What It Covers | Claims from clinical treatment errors | Bodily injury/property damage on premises |
| Typical Claim Example | Patient injured by improper spinal mobilization | Patient trips over equipment cord in hallway |
| Coverage Limits | $1M/$3M standard | $1M/$2M standard |
| Annual Premium Range | $1,200 - $4,000 per provider | $500 - $2,500 per location |
| Who Needs It | Every licensed PT providing treatment | Every business with a physical location |
| Covers Legal Defense | Yes | Yes |
| Covers Regulatory Board Actions | Often yes, with endorsement | No |
Both policies are essential. One covers what happens on your treatment table, the other covers what happens on your floor. Carrying only one leaves a dangerous blind spot.
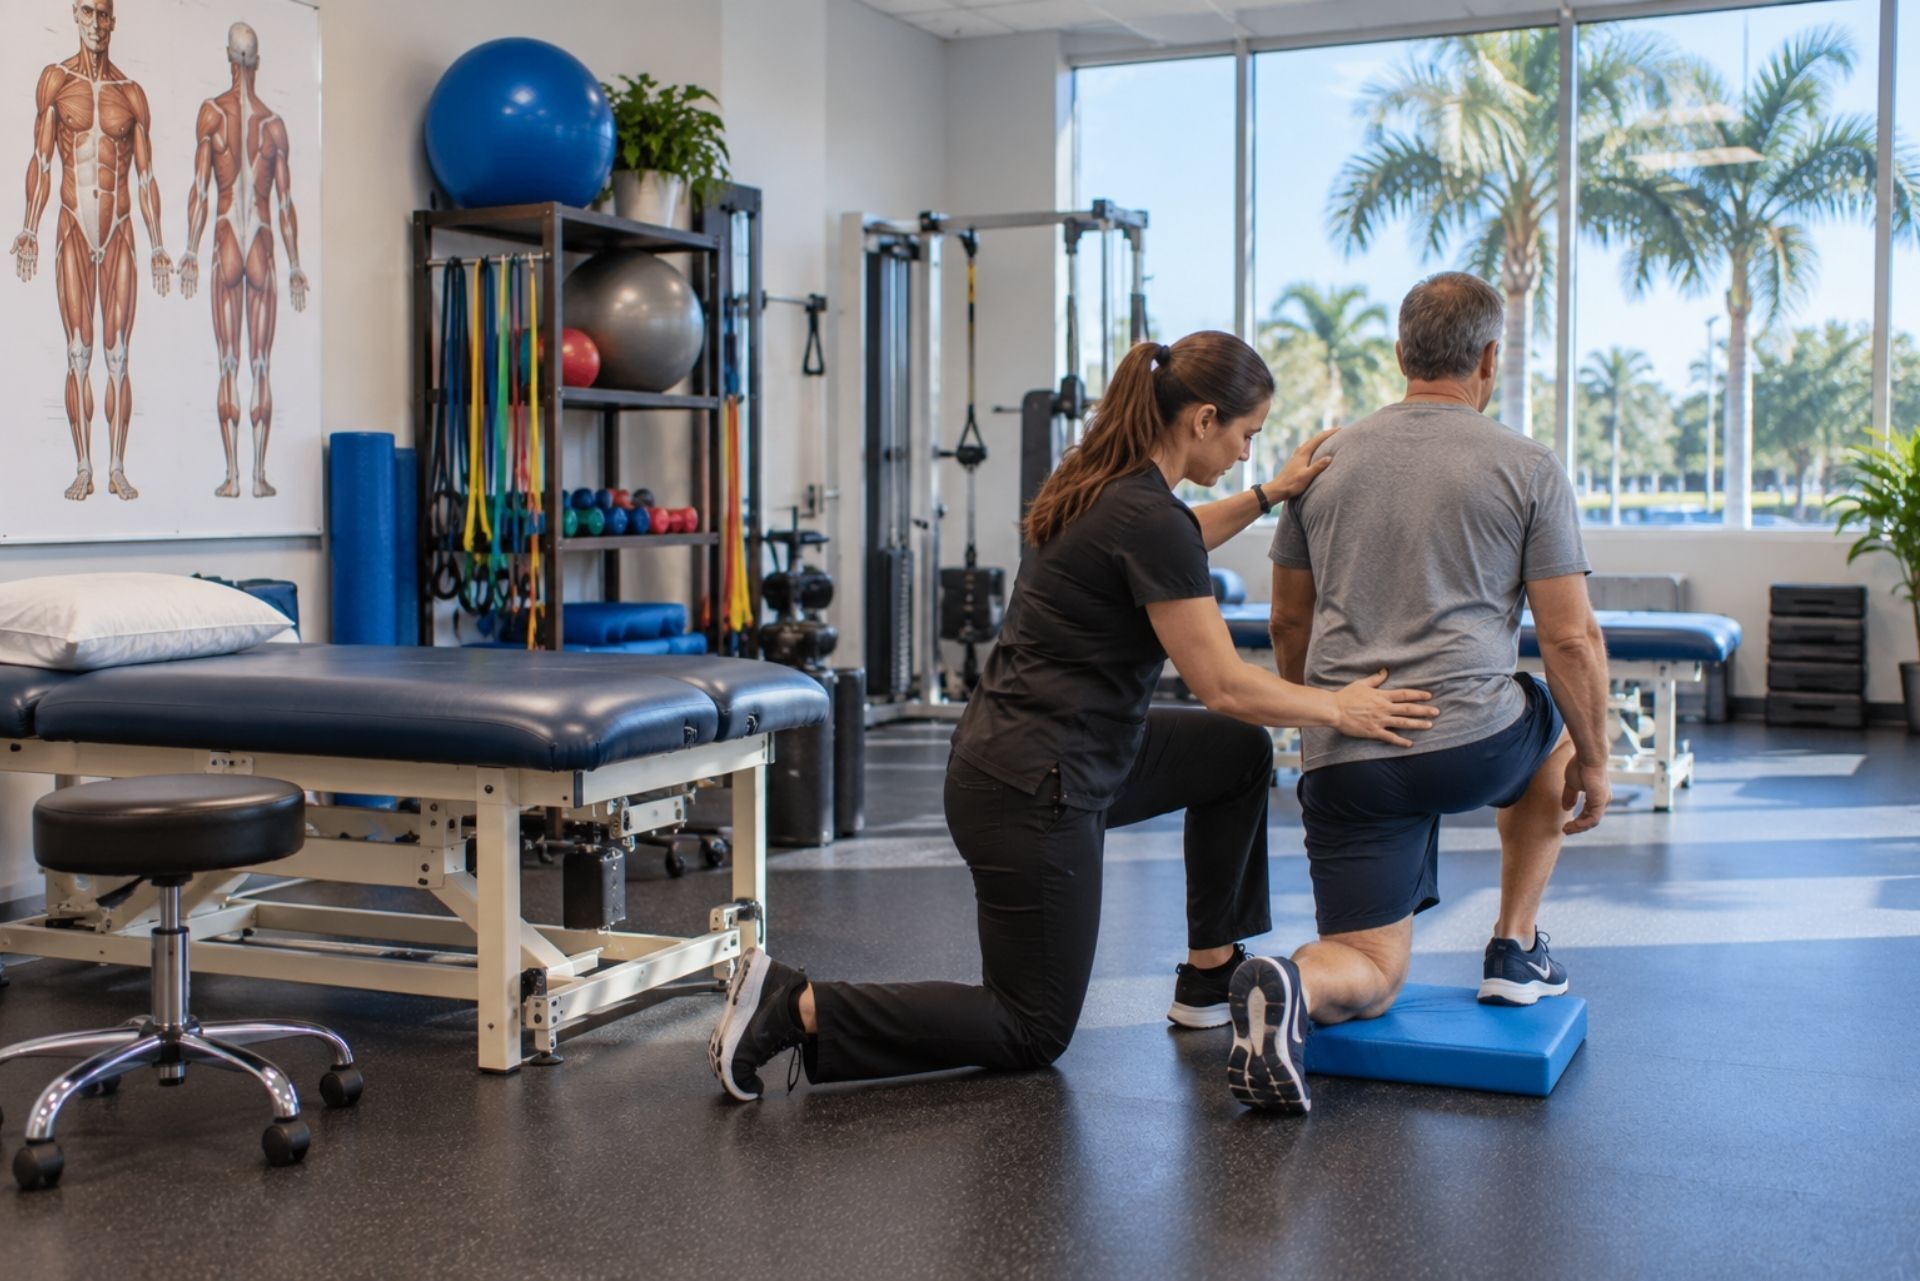
Protecting Against Modern Digital Risks
Clinical risks aren't the only threats facing your practice. Digital vulnerabilities and employment-related claims have become major cost drivers for healthcare businesses in Florida.
Cyber Liability and HIPAA Data Breaches
PT clinics store protected health information, including patient names, diagnoses, treatment records, Social Security numbers, and insurance details. A data breach can trigger HIPAA penalties ranging from $100 to $50,000 per violation, with annual maximums reaching $1.5 million per violation category. Cyber liability insurance covers breach notification costs, credit monitoring for affected patients, forensic investigation, legal defense, and regulatory fines.
Ransomware attacks on small healthcare practices have increased sharply since 2024, with attackers specifically targeting clinics that use older electronic health record systems. If your practice uses cloud-based scheduling, telehealth platforms, or electronic billing, you're exposed. Cyber liability premiums for small PT clinics typically range from $500 to $2,000 annually, a fraction of what a single breach could cost you out of pocket.
Employment Practices Liability Insurance (EPLI)
EPLI covers claims from employees alleging wrongful termination, discrimination, harassment, or retaliation. Even a baseless claim can cost $25,000 or more in legal defense fees. Florida is an at-will employment state, but that doesn't protect you from federal employment law claims under Title VII, the ADA, or the FMLA.
PT clinics with small teams often assume employment disputes won't happen to them. The reality is that tight-knit workplaces can generate friction quickly, especially during staff turnover or when performance issues arise. EPLI premiums depend on your employee count and claims history, but most small practices pay between $800 and $3,000 per year.
Common Questions About Physical Therapy Insurance
FAQ: Cost, Coverage, and Claims
How much does insurance for a PT clinic in Florida typically cost? A comprehensive package covering professional liability, general liability, property, and workers' comp usually runs between $5,000 and $15,000 annually for a single-location clinic with 3 to 8 employees. Costs vary based on your revenue, claims history, and location.
Does my personal PT license come with malpractice coverage? No. Your Florida PT license doesn't include any insurance. You need to purchase professional liability coverage separately, either through your clinic's policy or an individual policy.
What happens if a patient files a PIP-related complaint against my clinic? PIP disputes often involve billing disagreements rather than malpractice claims. Your professional liability policy may not cover billing fraud allegations. A separate errors and omissions endorsement or a dedicated PIP billing compliance program can help. The 14-day rule for PIP claims creates strict timelines that affect both patients and providers.
Are independent contractors at my clinic covered under my policy? Usually not. Independent contractor PTs and PTAs typically need their own professional liability coverage. Your general liability policy covers them while they're on your premises, but clinical malpractice claims against them won't be covered under your clinic's professional liability unless they're specifically named.
Do I need flood insurance even if I'm not in a flood zone? Florida's weather patterns make flood coverage worth considering regardless of your FEMA zone designation. Standard commercial property policies exclude flood damage entirely. A separate flood policy through the NFIP or a private insurer fills this gap.
Can I reduce my workers' comp premiums? Yes. Florida's workers' compensation system rewards safe workplaces through experience modification rates. Implementing a formal safety program, conducting regular ergonomic assessments for your staff, and maintaining a clean claims history can lower your premiums over time.
Making the Right Choice for Your Practice
Getting the right insurance for your Florida PT clinic isn't about buying the cheapest policy or checking a compliance box. It's about building a coverage portfolio that matches your actual risk profile : your location, your patient population, your equipment, your staff size, and your digital infrastructure.
Start by auditing your current policies against the coverage types outlined above. Check for gaps between professional and general liability. Verify your property policy covers wind damage with a deductible you can actually afford. Confirm your workers' comp compliance. And don't ignore cyber liability, because a single ransomware attack can cost more than years of premiums.
Talk to a broker who specializes in healthcare or physical therapy clinic insurance in Florida specifically. Generic commercial agents often miss the nuances of PIP billing exposure, HIPAA compliance requirements, and hurricane-related property risks that are unique to this state. Your practice is your livelihood. Protect it with coverage that actually fits.
ABOUT THE AUTHOR:
MONTREAL MORAND
With over 20 years of leadership experience in the insurance industry, I’ve dedicated my career to helping clients and agents make informed, confident decisions about their coverage. I’ve led high-performing teams, managed more than $128 million in premium, and earned multiple national awards for excellence. Today, my mission remains the same — to educate, empower, and provide dependable protection for the communities we serve.
Contact Us
Protect the Things That Matter Most
Reliable Coverage for Your Home & Lifestyle
Home Insurance
Protect your home, belongings, and personal liability with reliable coverage.
Stronger Coverage for Your Operations
Essential Protection for Your Company
Coverage built for businesses that depend on people, property, and equipment.
Industries We Support
Insurance for Everyday Local Businesses
Simple, reliable protection for the people who keep our communities running.
Plumbers
Plumbers Insurance
Protection for job-site hazards, tools, and customer property.
Restaurants
Restaurants Insurance
Coverage for fire risks, food inventory, and general liability.
HVAC Contractors
HVAC Contractors Insurance
Insurance for service vehicles, equipment, and installation risks.
Frequently Asked Questions
Helpful Answers to Common Questions
Quick guidance to help you understand your coverage.
What types of insurance does Macpherson Insurance Agency offer?
We provide both personal and commercial insurance solutions. On the personal side: homeowners, automobile, condo, renters, windstorm, flood, excess flood, and more. On the commercial side: general liability, property, inland marine, ocean marine, workers compensation, and more.
Do you specialize in homeowners insurance in South Florida?
Yes. We specialize in homeowners coverage in South Florida and work with multiple carriers based on your property’s age, location and replacement cost.
What does “replacement cost” mean in a policy?
Replacement cost is the cost to rebuild your home to the same standard it had before a loss — not the market value of your property.
Why is it important that my insurer is licensed in Florida?
Licensed Florida insurers are continuously monitored for financial stability — if one fails, the Florida Insurance Guaranty Fund may reimburse insureds for unpaid claims up to a limit.
Can I lower my homeowners premium with discounts?
Yes — mitigation features like impact glass, storm shutters, roof straps, and approved sheathing may qualify you for significant credit reductions.
Do you offer payment plans or premium financing?
Yes. In many cases, payment plans and premium financing are available to make coverage more affordable and manageable over time.
From the Blog
Helpful Tips & Insurance Guidance
Articles created to make insurance easier to understand.


Contact Us
Phone
Location