See How We're Different
or call us: 305-669-5288
Every June, my phone starts ringing with the same question from guard-company owners across the county: if a named storm hits, can we staff it? The answer is usually yes — and then the harder question follows. Miami security company hurricane insurance has to keep up with what your firm actually does during an activation, not what your operation looked like the day the policy was written. Between hurricane season and the occasional civil-unrest call-out, South Florida guard firms scale faster than almost any service business I work with.
Emergency posts move faster than paperwork
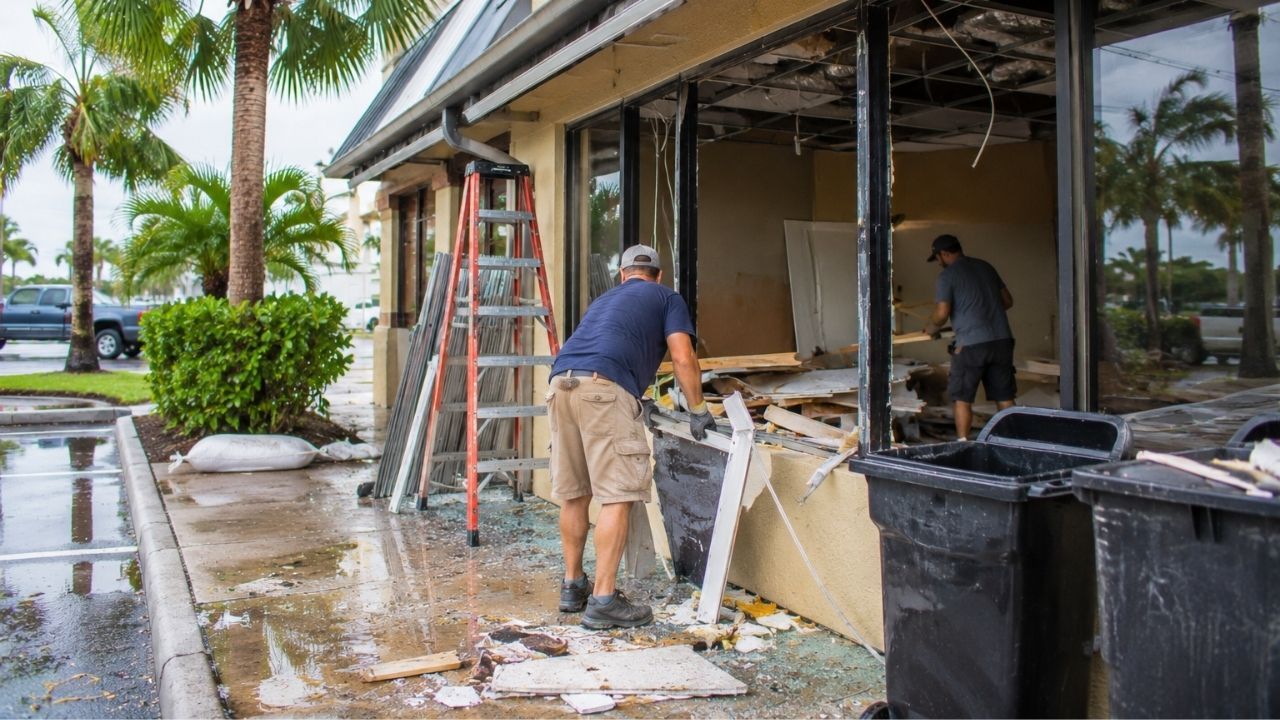
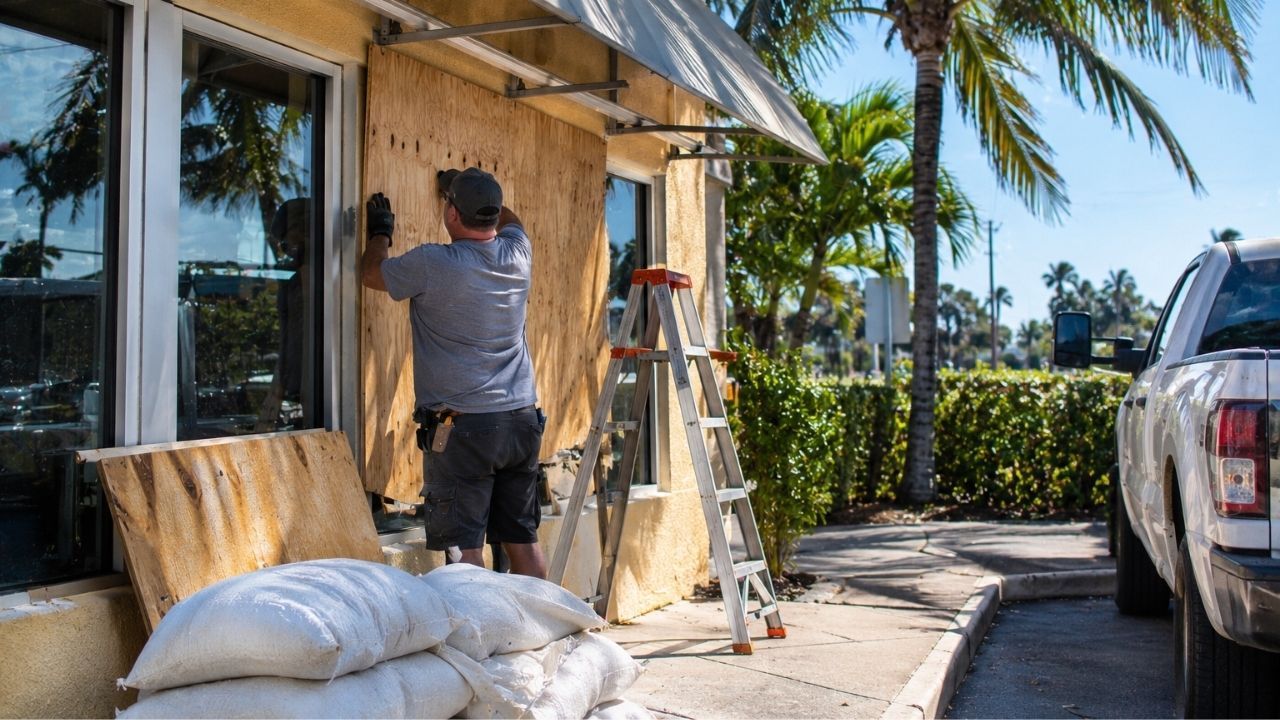
The Miami-Dade Department of Emergency Management coordinates countywide preparedness, response, and recovery, and hurricane season runs June 1 through November 30. When the county activates, private security firms fill the gaps: board-and-guard details at damaged storefronts, re-entry screening at gated communities and office parks, overnight posts at properties running without power or cameras.
That work arrives in hours, not weeks. A twelve-officer company can be fielding forty officers by the weekend, with rented vans running mobile patrol across three ZIP codes. Your carrier should understand that pattern before it happens — not at audit time.
What Miami security company hurricane insurance should match
I treat this as a fit exercise, not a shopping list. The things worth reviewing before the season builds:
• Surge staffing and payroll — temporary officers and heavy overtime change your exposure basis and your workers' comp reporting.
• Vehicles and mobile patrol — rented, borrowed, or employee-owned vehicles pressed into post duty are a common blind spot.
• Contractual language — hold-harmless and indemnity wording in emergency-response agreements, especially the ones signed under pressure at 2 a.m.
• Civil-unrest response work — different post orders and a different risk profile than a routine retail account.
None of that is a promise about what any particular policy does. It's the list I walk through with owners so nothing important goes unexamined.
Licensing is not something insurance replaces
Worth saying plainly: FDACS licenses Florida security officers — Class D for unarmed work, Class G for the statewide firearm license — under Chapter 493, Florida Statutes. Temporary unarmed and armed surge crews brought on for hurricane or civil-unrest response still have to hold the right licenses. Coverage sits alongside that requirement. It never stands in for it.
If your license file is clean but your coverage still reflects a smaller, calmer version of your company, that's the gap to close now — before the cone shows up on the evening news.
Come talk it through with me. Macpherson Insurance Agency offers a free insurance review for South Florida guard firms no price quote required, just an honest look at whether your program matches how you actually operate. Call 305-669-5288, email info@macphersonagency.com, or stop by 1390 S. Dixie Hwy, Suite 1209, Coral Gables. You can also learn more at Macpherson Insurance Agency.
This article is for educational purposes only. It is not insurance, legal, or regulatory advice, and it does not describe, modify, or guarantee coverage under any policy. Coverage depends on the terms of the policy actually issued. Please consult a licensed agent about your specific situation.