A single chafing dish tipping over at a beachfront wedding in Sarasota can turn a profitable Saturday night into a five-figure liability claim. The average property damage claim for caterers, like a scorching incident on a venue's hardwood floor,
runs approximately $4,300. That's before you factor in legal defense costs, medical bills, or the venue's demand for compensation. For Florida caterers specifically, the risk profile is shaped by hurricane season, year-round outdoor events, liquor service at nearly every booking, and a legal environment that shifts regularly. Understanding the full scope of insurance coverage you need, from
general liability and liquor liability to property protection, commercial auto, and workers' comp, isn't optional. It's the difference between surviving a bad night and closing your doors. This guide breaks down what Florida catering companies actually need, what it costs in 2026, and where operators most often get caught underinsured.
Essential Insurance Policies for Florida Caterers
Every catering operation carries a unique mix of risks, but a handful of policies form the foundation for any Florida-based food service business. Whether you're running a two-person operation out of a commissary kitchen in Jacksonville or managing a 40-person crew serving galas in Palm Beach, these policies aren't luxuries. They're the baseline.
General Liability and Product Liability
General liability (GL) is the policy that responds when a guest trips over your power cord, when your server spills red wine on a bride's gown, or when your setup damages a venue's property. Most Florida caterers carry at least $1 million per occurrence with a $2 million aggregate, though high-volume operations and venues in Miami-Dade or Broward often require higher limits according to insuranks.com.
Product liability, which is typically bundled into your GL policy, covers claims tied to the food itself. A guest gets sick from improperly stored shrimp? That's a product liability claim. Florida's heat and humidity make food safety a constant concern, and insurers know it. Your GL premium will reflect your annual revenue, the types of events you serve, and whether you do on-site cooking with open flames or simply deliver prepped trays.
Liquor Liability for Event Services
Florida's dram shop statute, Section 768.125, provides caterers with more protection than most states. The law generally shields businesses from liability for injuries caused by intoxicated adults they served. Liability only attaches if you "willfully and unlawfully" serve a minor or "knowingly" serve someone habitually addicted to alcohol.
That sounds like a strong shield, and it is, but it doesn't eliminate the need for liquor liability coverage. Even when the statute protects you from a final judgment, you still face the cost of defending yourself. Lawsuits get filed regardless of the law's protections, and defense costs alone make liquor liability essential for any caterer pouring drinks. If you serve alcohol at even a fraction of your events, this policy should be non-negotiable.
Commercial Auto and Hired/Non-Owned Coverage
Your personal auto policy won't cover an accident that happens while your team is hauling equipment to an event in a company van. Commercial auto insurance covers vehicles owned by your business, including box trucks, refrigerated vans, and cargo trailers. Florida's auto insurance market has been volatile, though the top five auto insurance groups are averaging an 8% rate decrease in 2026 after rates spiked over 30% in 2023.
Don't overlook hired and non-owned auto coverage. If an employee uses their personal car to pick up last-minute supplies and causes an accident, your business can be held liable. This endorsement fills that gap. It's inexpensive relative to the exposure it covers, and many caterers skip it until it's too late.
By: Montreal Morand
Founder & Managing Partner
Macpherson Insurance Agency
Florida-Specific Regulations and Requirements
Operating in Florida means dealing with state-specific rules that directly affect your insurance needs and costs. The regulatory environment here differs from most other states, and those differences can work for or against you.
Workers' Compensation Laws for Food Service
Florida law requires workers' compensation coverage for any business in the construction industry with one or more employees, and for non-construction businesses, including caterers, with four or more employees as stated by myfloridacfo.com. If you're running a crew of three, you're technically exempt, but carrying the coverage anyway protects you from personal injury lawsuits by employees.
The good news for Florida caterers in 2026 : rates keep dropping. The Florida Office of Insurance Regulation approved a 6.9% statewide rate decrease effective January 1, 2026, marking the ninth consecutive year of decreases. The NCCI has even proposed an additional 7.4% reduction for 2027 due to declining claim frequency and severity. That said, your individual rate depends on your payroll size, job classifications, and claims history. Kitchen staff and servers carry different risk profiles, and your experience modification factor can push your premium up or down significantly.
Venue Insurance Requirements and Certificates
Nearly every reputable venue in Florida will ask for a Certificate of Insurance (COI) before you set foot on their property. Most require you to list the venue as an "additional insured" on your general liability policy. Some venues, particularly upscale spots in Naples, Brickell, or St. Augustine, demand minimum limits of $2 million per occurrence or require separate liquor liability proof due to high property values and guest counts according to theinsurancekitchen.com.
Plan ahead. Requesting a COI from your insurer can take 24 to 48 hours, and last-minute scrambles lead to mistakes on certificates. Build COI requests into your event workflow at least a week before each booking. If you're doing 100+ events per year, ask your agent about a blanket additional insured endorsement, which automatically extends coverage to any venue without requiring individual certificate requests.
Comparing Basic vs. Comprehensive Coverage
The gap between a bare-minimum policy and a well-structured insurance program is where most claims fall through. A basic package might check the box for venue requirements, but it can leave you exposed in ways you won't discover until you file a claim.
Comparison Table : Essential vs. Extended Protection
| Coverage Area | Basic Package | Comprehensive Package |
|---|---|---|
| General Liability | $1,200 – $1,800 ($1M/$2M) | $1,800 – $3,000 ($2M/$4M) |
| Liquor Liability | $500 – $1,000 (Sublimit) | $1,500 – $3,500 (Standalone $1M) |
| Commercial Auto | $1,500 – $2,500 (Owned) | $2,500+ (Includes HNOA) |
| Property/Equipment | Business premises only | Includes inland marine for gear in transit |
| Workers' Comp | ~$1.40 per $100 payroll | Varies by payroll size |
| Umbrella/Excess | N/A | $500 – $1,500 per $1M layer |
| Spoilage Coverage | Not included | Covers food loss from equipment failure |
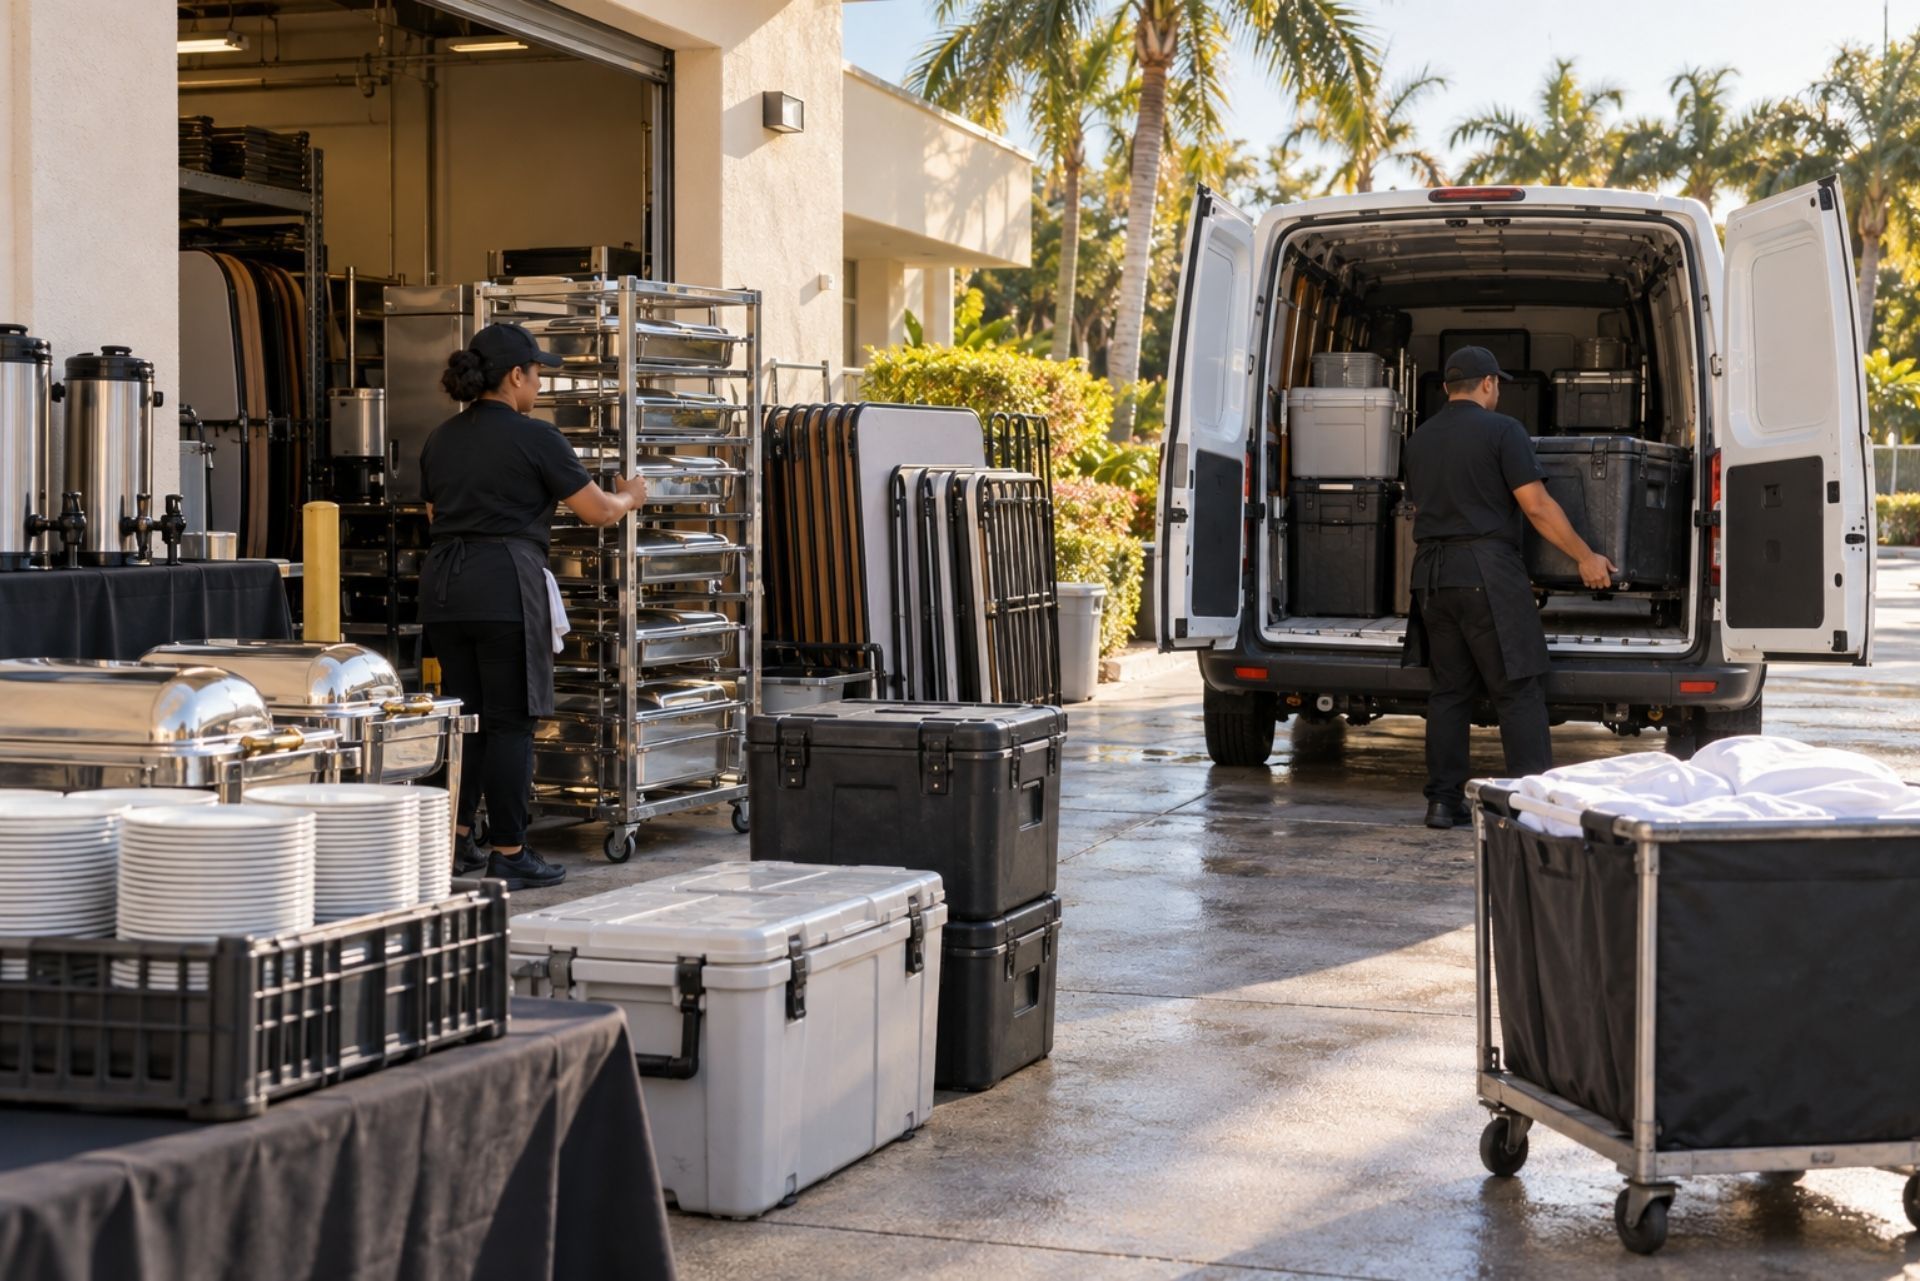
One of the most common gaps : equipment in transit. Caterers hauling expensive ovens, chafing dishes, and POS systems between events need inland marine coverage to protect gear while it's on the road. A standard property policy only covers items at your listed business location. If your $15,000 convection oven gets destroyed in a highway accident, a basic property policy won't pay a dime.
Your premium isn't a fixed number pulled from a chart. It's calculated based on a combination of factors specific to your operation, your location, and your history.
Annual Revenue and Payroll Impacts
Revenue is the primary rating basis for general liability. A caterer grossing $500,000 annually will pay significantly more than one bringing in $150,000, because higher revenue generally means more events, more guests, and more exposure. Payroll drives your workers' compensation premium. The more you pay employees, the higher the premium, though the declining Florida workers' comp rates in 2026 soften that impact.
Your claims history matters just as much. A clean three-year record can earn you preferred rates, while even one significant claim can increase your premiums by 15% to 25% at renewal according to theinsurancekitchen.com. Keep detailed incident reports for every event, even minor ones. Insurers reward businesses that demonstrate proactive risk management.
Off-Site vs. On-Site Preparation Risks
Caterers who cook on-site at venues carry more risk than those who prepare everything in a commissary kitchen and deliver finished product. Open-flame cooking at outdoor events introduces fire risk. Frying stations near guests create burn exposure. Even the type of fuel you use, propane versus electric, affects your rating.
Florida's outdoor event season runs essentially year-round, which means your exposure to weather-related risks doesn't take a break either. Hurricane season from June through November adds a layer of concern for outdoor equipment and tented events. If you store equipment in a coastal warehouse, wind and flood exposure can increase your property premiums. Insurers in Southwest Florida and the Keys will scrutinize your storage locations carefully.
Common Questions About Catering Insurance
Frequently Asked Questions
Do I need insurance for a small catering side hustle? Yes. Even a one-person operation faces liability if a guest gets sick or a venue's property is damaged. Most venues won't book you without proof of coverage regardless of your business size.
Can I use my homeowner's policy to cover catering equipment? Homeowner's policies exclude business use. If you're storing commercial equipment at home, you need a separate business property or inland marine policy to cover it.
How does Florida's tort reform affect my premiums? Recent tort reform has contributed to declining claim costs statewide, which is one reason workers' comp rates have dropped for nine consecutive years. The full impact on liability premiums is still unfolding, but the trend favors lower costs for well-run operations.
Is liquor liability required by law in Florida? It's not a state mandate, but most venues and event planners require it contractually. Given that defense costs alone can reach five figures even when the law is on your side, carrying the coverage is a practical necessity.
What happens if my employee gets hurt and I don't have workers' comp? If you're required to carry it and don't, you face fines, stop-work orders, and personal liability for the employee's medical bills and lost wages. Florida's Division of Workers' Compensation actively investigates non-compliant employers.
Does my policy cover food spoilage from a power outage?
Only if you've added spoilage coverage. Standard property policies don't cover food loss from equipment breakdown or power failure. This endorsement is inexpensive and worth adding if you store significant inventory.
Before You Buy a Policy
Getting insurance for your Florida catering company right means more than just buying the cheapest package that satisfies venue requirements. It means matching your coverage to your actual risk profile : the types of events you serve, whether you pour alcohol, how many employees you run, and where you store and transport your equipment.
Start by auditing your current exposure. List every vehicle, every piece of equipment that leaves your kitchen, every venue type you serve, and your peak staffing numbers. Bring that information to an agent who specializes in food service or hospitality, not a generalist who writes auto policies on the side. Ask specifically about inland marine coverage, hired and non-owned auto, and spoilage endorsements, because these are the gaps that catch caterers off guard.
Florida's insurance market in 2026 is actually working in your favor, with declining workers' comp rates and moderating auto premiums. Take advantage of the pricing environment to build out a comprehensive program rather than settling for the minimum. The cost difference between basic and full protection is often smaller than operators expect, and it's always smaller than the cost of an uncovered claim.
ABOUT THE AUTHOR:
MONTREAL MORAND
With over 20 years of leadership experience in the insurance industry, I’ve dedicated my career to helping clients and agents make informed, confident decisions about their coverage. I’ve led high-performing teams, managed more than $128 million in premium, and earned multiple national awards for excellence. Today, my mission remains the same — to educate, empower, and provide dependable protection for the communities we serve.
Contact Us
Protect the Things That Matter Most
Reliable Coverage for Your Home & Lifestyle
Home Insurance
Protect your home, belongings, and personal liability with reliable coverage.
Stronger Coverage for Your Operations
Essential Protection for Your Company
Coverage built for businesses that depend on people, property, and equipment.
Industries We Support
Insurance for Everyday Local Businesses
Simple, reliable protection for the people who keep our communities running.
Plumbers
Plumbers Insurance
Protection for job-site hazards, tools, and customer property.
Restaurants
Restaurants Insurance
Coverage for fire risks, food inventory, and general liability.
HVAC Contractors
HVAC Contractors Insurance
Insurance for service vehicles, equipment, and installation risks.
Frequently Asked Questions
Helpful Answers to Common Questions
Quick guidance to help you understand your coverage.
What types of insurance does Macpherson Insurance Agency offer?
We provide both personal and commercial insurance solutions. On the personal side: homeowners, automobile, condo, renters, windstorm, flood, excess flood, and more. On the commercial side: general liability, property, inland marine, ocean marine, workers compensation, and more.
Do you specialize in homeowners insurance in South Florida?
Yes. We specialize in homeowners coverage in South Florida and work with multiple carriers based on your property’s age, location and replacement cost.
What does “replacement cost” mean in a policy?
Replacement cost is the cost to rebuild your home to the same standard it had before a loss — not the market value of your property.
Why is it important that my insurer is licensed in Florida?
Licensed Florida insurers are continuously monitored for financial stability — if one fails, the Florida Insurance Guaranty Fund may reimburse insureds for unpaid claims up to a limit.
Can I lower my homeowners premium with discounts?
Yes — mitigation features like impact glass, storm shutters, roof straps, and approved sheathing may qualify you for significant credit reductions.
Do you offer payment plans or premium financing?
Yes. In many cases, payment plans and premium financing are available to make coverage more affordable and manageable over time.
From the Blog
Helpful Tips & Insurance Guidance
Articles created to make insurance easier to understand.



Contact Us
Phone
Location