See How We're Different
or call us: 305-669-5288
Ask five Florida roofers what they pay for general liability and you'll hear five very different numbers, sometimes from contractors working the same Tampa subdivision. That spread isn't random. Carriers price every contractor policy from a short list of inputs, and once you understand them, the quote in your inbox stops looking like a guess.
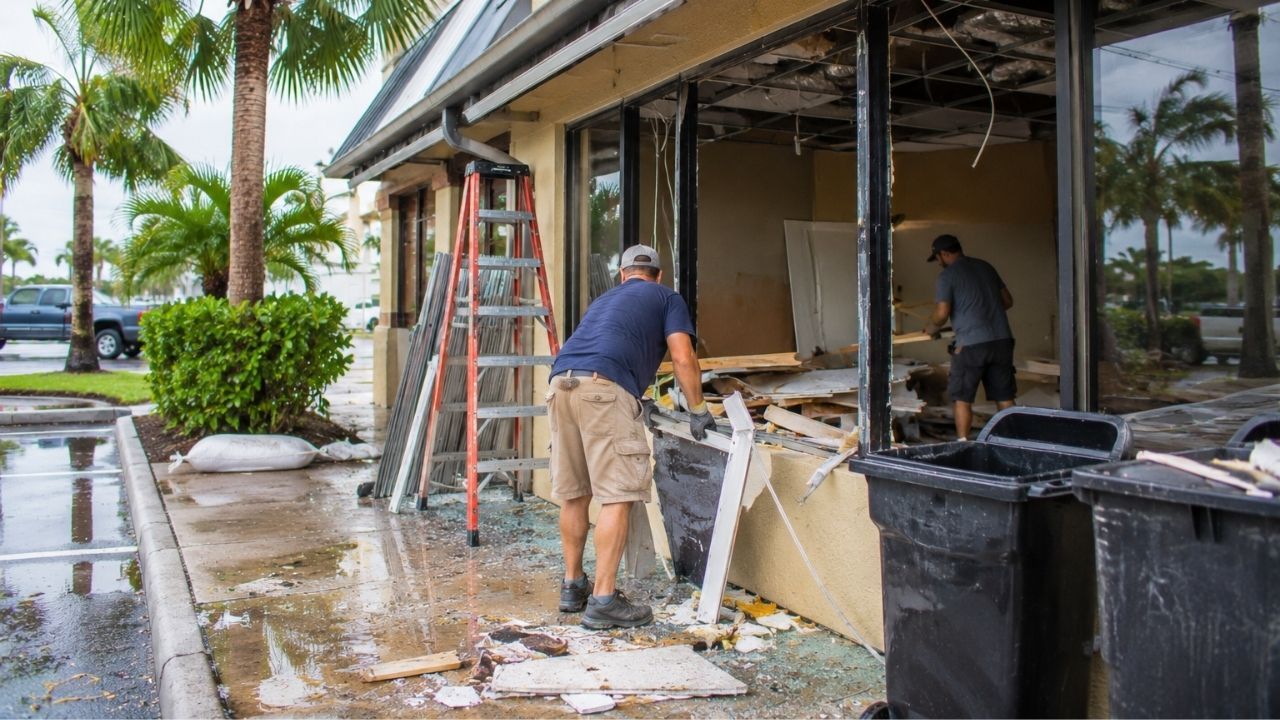
Florida adds its own twist. Hurricane rebuild demand, a long history of construction defect litigation, and recent tort reform all affect what underwriters charge a drywall sub in Orlando versus a pool builder in Naples. The state's licensing board also sets a coverage floor that you can't drop below without risking your license.
This guide breaks down how GL insurance costs for Florida contractors are actually built. It covers the exposure bases carriers use, the class codes that set your base rate, the limit and deductible choices you control, and the realistic price points available for solo operators. If you've ever wondered why your premium jumped after a renewal audit, or why a competitor pays less for similar work, the answers are below. You'll also find a short FAQ and a checklist for reviewing your current policy before your next renewal.
Understanding Florida Contractor Insurance Costs
General liability covers third-party bodily injury and property damage arising from your work. Picture a ladder falling onto a homeowner's car in Coral Gables, a client tripping over your extension cord, or a plumbing repair that floods a condo below. GL responds to those claims. It doesn't cover your own tools, your employees' injuries, or faulty design advice. Those need inland marine, workers' comp, and E&O policies.
Florida sets a legal minimum. Under F.S. 489.115, certified and registered contractors must carry at least $300,000 in bodily injury and $50,000 in property damage coverage, and a lapse triggers automatic license suspension. That's where operators get caught: a missed payment or non-renewal notice can sideline your license mid-project.
The catch is that the statutory minimum rarely satisfies anyone you actually work for. General contractors, property managers, and HOAs in places like Brickell or The Villages routinely require $1 million per occurrence before you set foot on site. So your real cost question isn't "what's the minimum," it's "what will my clients demand, and what does that limit cost for my trade?"
The Primary Math: Payroll, Receipts, and Class Codes
Every GL premium starts with a simple formula: exposure base, divided by a unit (usually $1,000), multiplied by a rate tied to your class code. Then the underwriter applies credits or debits for your experience, claims history, and Florida-specific factors.
How Class Codes Define Your Risk Level
Class codes, typically from the ISO General Liability classification system, describe what you actually do. A carpentry contractor doing interior trim sits in a very different code than one framing multistory residential projects. Roofing, especially on residential structures, carries some of the heaviest rates in the industry because falls, water intrusion, and completed operations claims are common.
Misclassification is one of the most common mistakes contractors make. If you're coded as "interior painting" but you also pressure-wash and paint exteriors from scaffolding, the carrier can reclassify you at audit and bill the difference. Worse, they may dispute a claim tied to work outside your listed operations. Describe every service you perform, even the ones that make up 10% of your revenue.
Projecting Annual Gross Receipts and Payroll
The exposure base is either payroll or gross receipts, depending on the carrier and class. Admitted and preferred markets typically rate on payroll, while many excess and surplus lines carriers, common in Florida's tougher trades, rate on gross receipts or subcontracted costs.
Here's what that means for you : your application estimate drives your deposit premium, and a year-end audit reconciles it. Underestimate receipts to get a cheaper quote and you'll face a surprise bill. Keep these records ready:
- Payroll by class code, excluding overtime premium where the carrier allows
- Gross receipts, separated by trade if you perform multiple operations
- Certificates of insurance from every subcontractor you hire
- Payments to uninsured subs, which carriers often add to your exposure
Key Rating Factors Specific to the Florida Market
Florida underwriters look at the same basics as carriers elsewhere, but several state conditions push rates around in ways contractors from Georgia or Ohio wouldn't expect.
- Litigation climate. Florida spent years as one of the most expensive liability states. Reforms passed in 2022 and 2023 are changing that, with insurance-related lawsuit filings falling 23% in 2024 and another 25% in the first half of 2025. Supporters argue the reforms are bringing balance to the civil justice system, though contractors shouldn't expect overnight price drops, since carriers price on several years of loss data.
- Hurricane rebuild work. Post-storm demand pulls new and out-of-area contractors into roofing and restoration. Underwriters scrutinize experience, licensing, and whether you're taking on work outside your normal scope.
- Completed operations exposure. Florida's statute of repose allows construction defect claims years after a job closes. Residential work, especially condos, draws heavy surcharges or exclusions.
- Coastal conditions. Saltwater corrosion and moisture intrusion drive water damage claims for HVAC contractors, window installers, and roofers along the Gulf and Atlantic coasts.
- Claims history and years in business. A five-year clean loss run often earns more credit than any other single factor.
One thing to keep in mind is exclusions. A cheap quote may exclude residential work, height over three stories, or subcontractor claims. That isn't savings. It's a coverage gap.
Comparing Coverage Limits and Deductible Impacts
Limits and deductibles are the two levers you directly control, and they work differently than most contractors assume.
Raising limits costs less than people expect because the first dollars of coverage carry most of the claim frequency. Large claims are rarer, so each additional layer gets cheaper per dollar of protection. Deductibles behave the opposite way. Florida GL policies often use per-claim deductibles, and many surplus lines carriers set them at a fixed level that you can't lower. Raising a deductible may trim your premium, but only modestly, and you'll owe that amount on every claim, including small property damage incidents your crew could have avoided.
Watch for defense costs too. Some policies erode the limit with legal fees, meaning a $1 million limit shrinks as attorneys bill. Ask whether defense is "outside the limits."
Common Limit Options: $1M vs $2M Comparison
| Feature | State Minimum | $1M / $2M | $2M / $4M |
|---|---|---|---|
| Per occurrence | $300K BI / $50K PD | $1M | $2M |
| Meets license law | Yes | Yes | Yes |
| Accepted by most GCs | Rarely | Usually | Yes |
| Commercial and condo work | No | Sometimes | Often required |
| Relative cost | Lowest | Moderate increase | Higher, often via umbrella |
Moving from a $300,000 limit to $1,000,000 typically adds roughly $100 to $300 a year. For most trades, that's the best-value upgrade available.
Sample Premiums for Common Florida Trades
Real numbers depend on your exposure base, so be wary of anyone quoting a flat "average" without asking about payroll or receipts. That said, there's a useful anchor at the low end : solo operators and independent contractors in Florida typically pay $500 to $900 a year in annual premiums. Add roughly $100 to $300 to step up to a $1 million limit.
Beyond that floor, trade risk drives cost. Here's how common trades generally rank relative to each other:
| Trade | Relative Risk | Common Cost Drivers |
|---|---|---|
| Handyman, light carpentry | Lower | Minor property damage claims |
| Interior painting | Lower | Overspray, client property damage |
| Electrical | Moderate | Fire claims, completed operations |
| Plumbing | Moderate | Water damage, condo leaks |
| HVAC | Moderate | Water intrusion, fire, coastal corrosion |
| Pool construction | Higher | Drowning exposure, defect claims |
| General contracting | Higher | Subcontractor exposure |
| Roofing | Highest | Falls, water intrusion, storm work |
Consider two scenarios. A solo painter in Sarasota with no employees and no subs will likely land near that $500 to $900 range. A Fort Myers roofing company with a crew and active post-hurricane residential contracts will pay many multiples of it, likely through a surplus lines carrier. Get trade-specific quotes rather than relying on any single published figure.
Frequently Asked Questions About Florida GL Costs
What's the cheapest GL policy that keeps my Florida license active? You need at least $300,000 bodily injury and $50,000 property damage under state law. Most clients will still require $1 million, so the cheapest policy often isn't usable.
Why did my premium go up after the audit? Your actual payroll or receipts came in higher than your estimate, or you paid uninsured subcontractors. The carrier bills the difference at your class code rate.
Can I pay monthly? Many carriers and premium finance companies offer installments. Just know a missed payment can cancel the policy and suspend your license.
Will tort reform lower my rates? It may help over time as lawsuit volume drops. Carriers react slowly, so expect gradual changes rather than an immediate cut.
Do I need GL if I'm a one-person operation? Yes, if you hold a Florida contractor license. Solo operators typically pay among the lowest premiums in the market.
Does GL cover my own tools?
No. You'll need inland marine or tools and equipment coverage for that.
Making the Right Choice for Your Contracting Business
Your premium comes down to what you do, how much of it you do, and how much protection you buy. Class codes set the base rate, payroll or receipts set the volume, and Florida's litigation history, storm exposure, and completed operations risk shape the final number. Limits are cheaper to raise than most contractors assume, while low quotes often hide exclusions that won't cut it when a claim hits.
Before your next renewal, run through this checklist:
- Confirm every service you perform is listed under the correct class code.
- Compare your projected receipts and payroll against last year's audit.
- Collect certificates from every subcontractor.
- Check for residential, height, or subcontractor exclusions.
- Verify your limits meet the requirements in your current contracts.
- Set reminders so coverage never lapses.
Talk to an independent agent who writes Florida contractor accounts regularly. The right policy protects your license as much as your balance sheet.