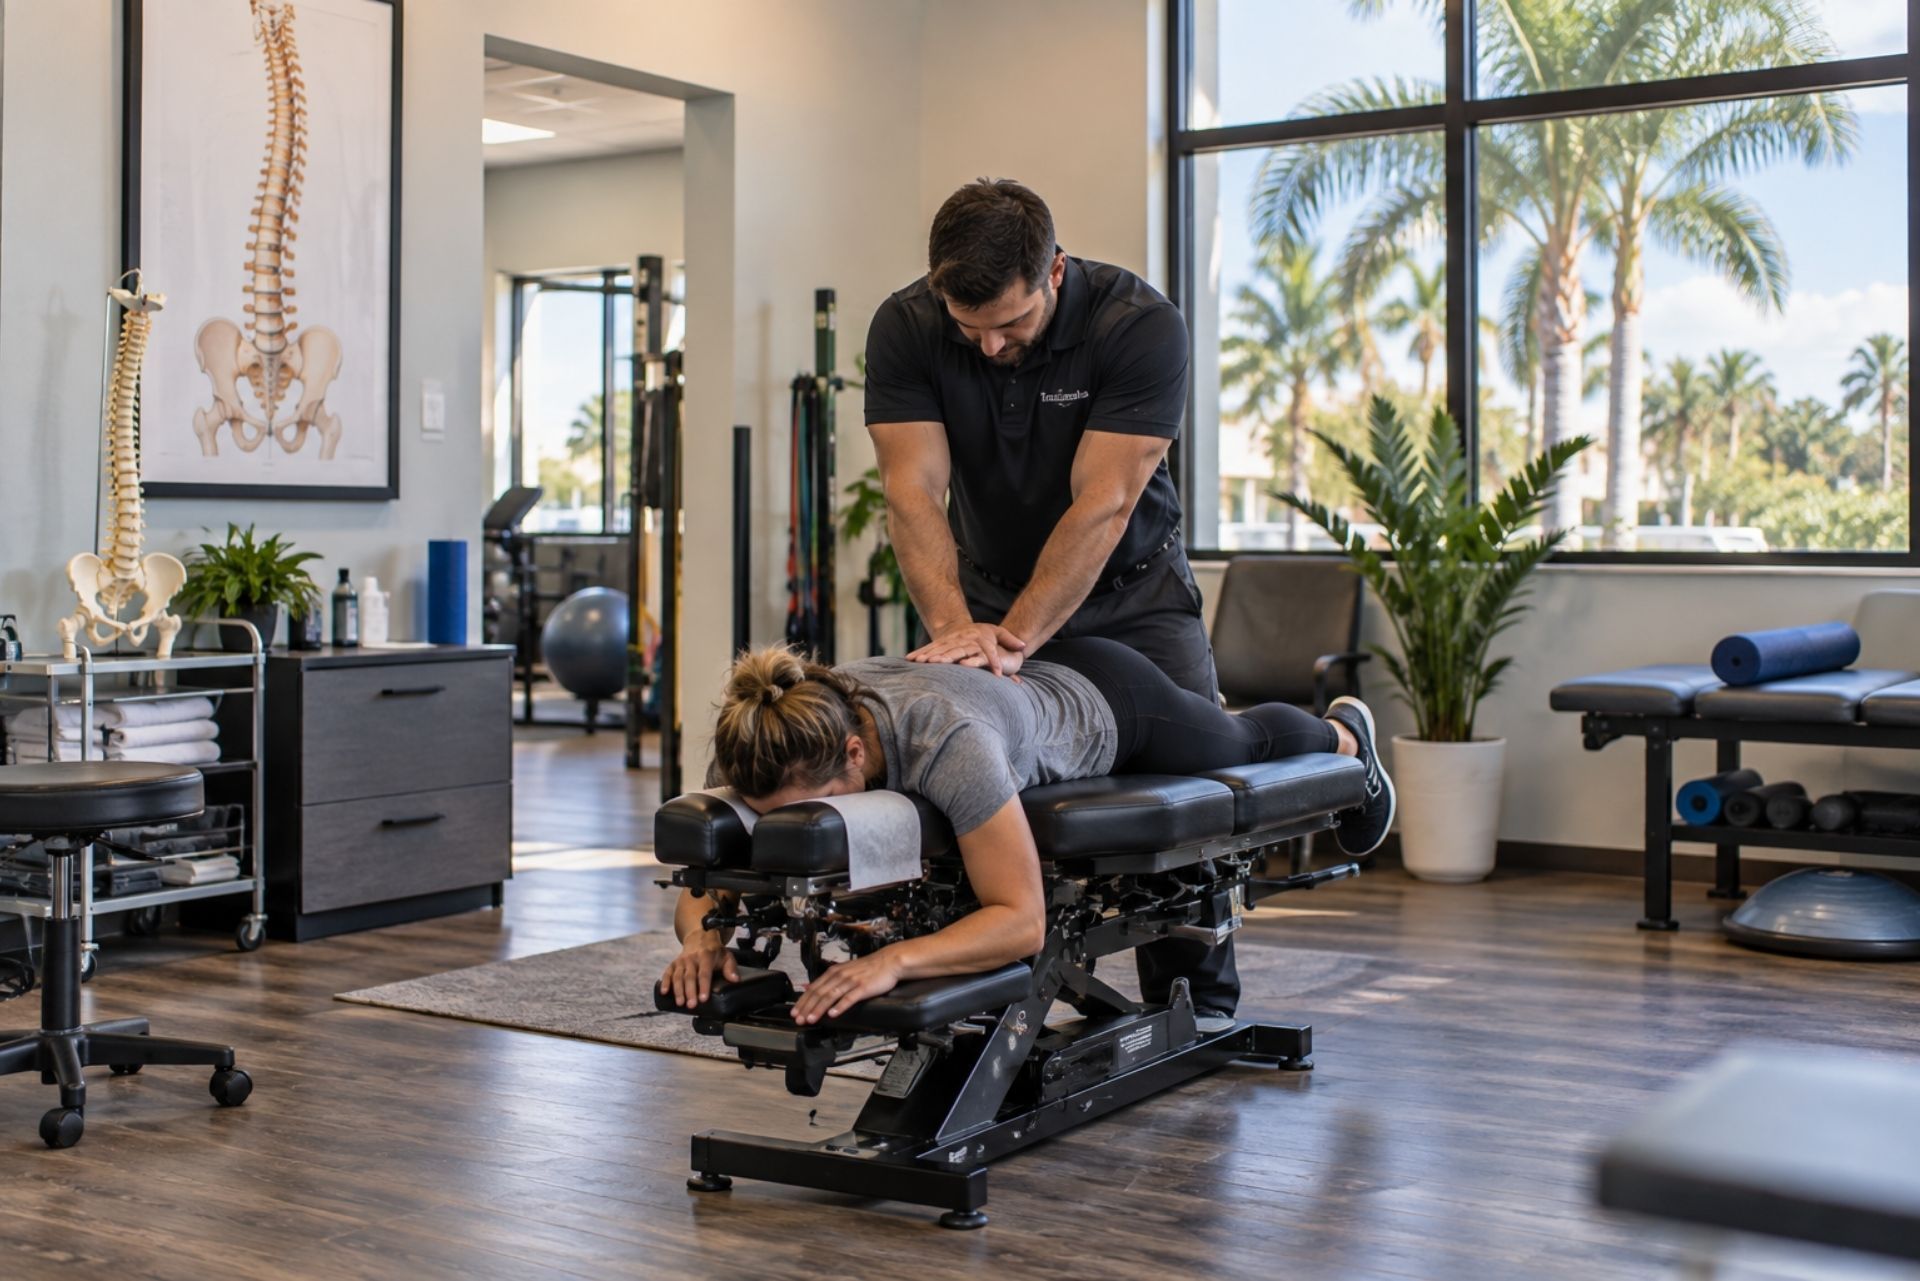
Running a chiropractic practice in Florida means dealing with risks that most business owners never think about. A patient claims an adjustment worsened a herniated disc. A delivery driver slips on a wet lobby floor during hurricane season. A ransomware attack locks your entire patient records system. Each of these scenarios can cost tens of thousands of dollars or more, and a single gap in your insurance coverage is all it takes to put your practice at serious financial risk.
Florida's chiropractic industry is growing, with over 7,000 licensed practitioners statewide and increasing demand for non-surgical pain management. That growth brings competition, higher patient volumes, and greater exposure to claims. Whether you're opening your first clinic in Jacksonville or managing a multi-provider office in Boca Raton, the right insurance package isn't optional. It's the foundation your practice stands on.
Getting your insurance for a Florida chiropractic clinic right means understanding what the state requires, what your specific practice needs, and where most chiropractors leave
dangerous coverage gaps. This guide breaks all of that down.
Essential Insurance Coverage for Florida Chiropractors
Every chiropractic clinic faces a distinct mix of clinical, operational, and property-related risks. Your insurance portfolio needs to address all three categories, not just the ones that feel most urgent. A single uncovered claim can drain your savings faster than a slow quarter ever could.
The three foundational policies for any chiropractic practice are professional liability, general liability, and business personal property coverage. Each one protects against a different type of loss, and none of them fully replaces the others. Think of them as three legs of a stool: remove one, and the whole thing tips over.
Professional Liability and Malpractice Insurance
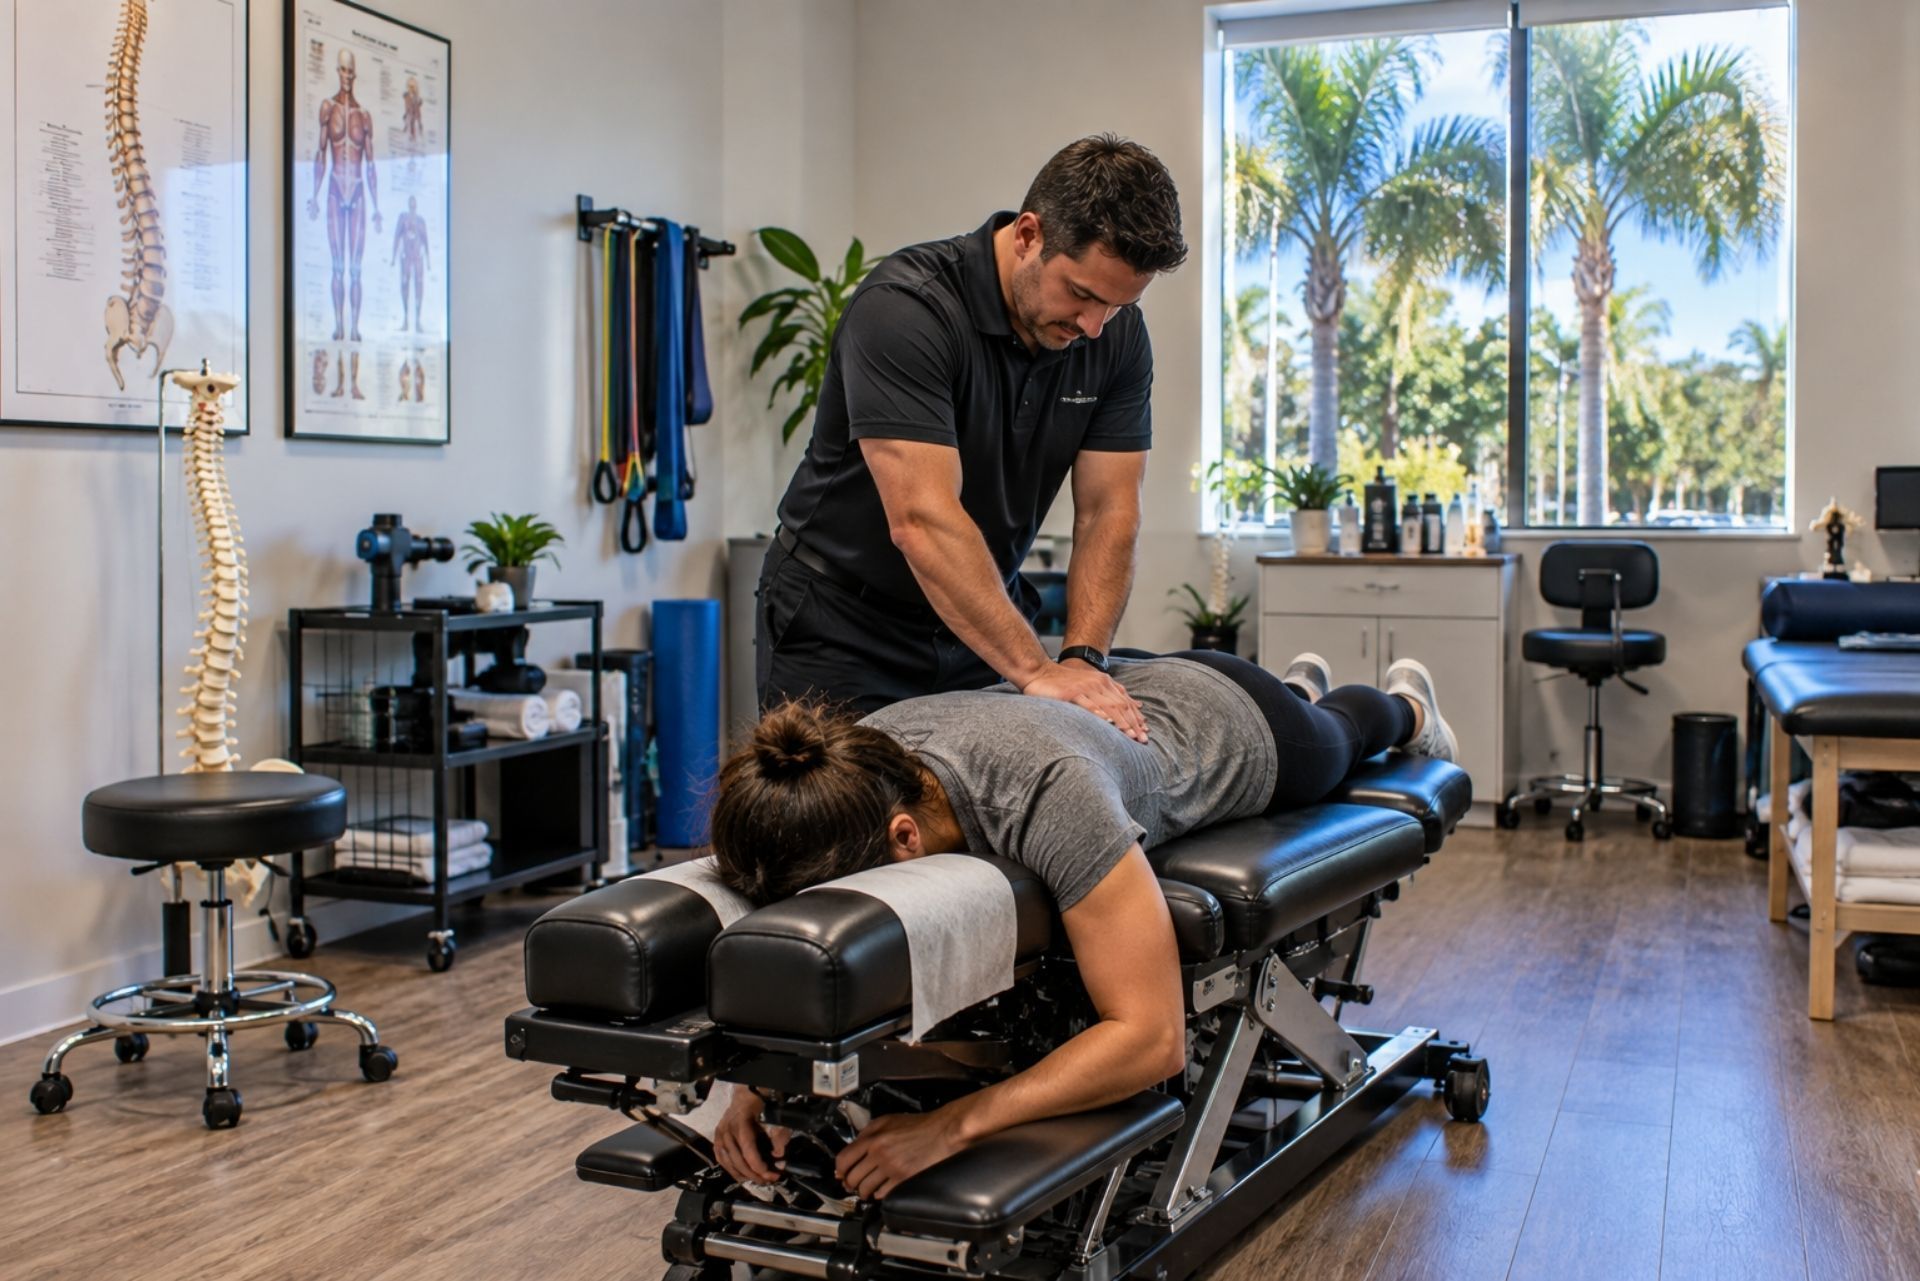
This is the policy that protects you when a patient alleges your treatment caused harm. In chiropractic care, common malpractice claims involve spinal manipulation injuries, failure to diagnose an underlying condition, or inadequate informed consent. Florida courts have seen cases where chiropractors were held liable for stroke symptoms following cervical adjustments, with settlements reaching six figures.
Your professional liability policy covers legal defense costs, settlements, and court judgments. Most Florida chiropractors carry limits of $1 million per occurrence and $3 million aggregate. The healthcare professional liability market has tightened in recent years, with underwriters scrutinizing claim histories more closely. If you've had a prior claim, expect higher premiums, but don't let that tempt you into lower limits.
One mistake chiropractors often make is assuming their malpractice policy covers associates or independent contractors working in the clinic. It usually doesn't. Each treating provider typically needs their own professional liability policy, or you need to add them as named insureds on yours.
General Liability for Clinic Premises
General liability covers bodily injury and property damage claims that happen on your premises but aren't related to treatment. The classic example: a patient trips over a loose floor mat in your waiting room and breaks a wrist. That's not a malpractice claim. It's a premises liability claim, and your professional liability policy won't pay for it.
This policy also covers advertising injury claims, like if a competitor alleges your marketing materials contain defamatory statements. For Florida clinics, hurricane-related water intrusion that damages a neighboring tenant's space can trigger general liability claims too. Most practices carry $1 million per occurrence with a $2 million aggregate.
Business Personal Property Coverage
Your clinic is full of expensive equipment: adjustment tables, digital X-ray systems, cold laser therapy units, EHR workstations. A standard commercial property policy covers these items against fire, theft, vandalism, and certain weather events. But here's where Florida clinics get caught: standard policies exclude flood and named windstorm damage.
If your clinic sits in a flood zone anywhere near the coast from Tampa to Miami, you need a separate flood policy through the NFIP or a private carrier. Wind coverage may require a separate policy or endorsement depending on your county. Don't assume your landlord's building policy covers your equipment inside the space. It almost never does.
By: Montreal Morand
Founder & Managing Partner
Macpherson Insurance Agency
Florida State Requirements and Legal Mandates
Florida imposes specific insurance and financial responsibility requirements on chiropractic practices. Ignoring them doesn't just create risk: it can cost you your license.
Workers' Compensation Laws for Small Practices
Florida law requires workers' compensation coverage for any business with four or more employees, including the chiropractor if they're a corporate officer who hasn't filed an exemption. Many small practices try to skirt this by classifying staff as independent contractors, but the state's Division of Workers' Compensation actively investigates misclassification. Penalties include stop-work orders and fines of $1,000 per day.
Even if you have fewer than four employees, carrying workers' comp voluntarily is smart. A front desk employee who injures their back moving boxes of supplies could file a personal injury lawsuit against you if no workers' comp policy exists. The policy acts as a shield: it covers their medical bills and lost wages, and in exchange, they give up the right to sue you.
Financial Responsibility Requirements under Florida Law
Florida chiropractors must meet specific financial responsibility standards to maintain their license. The Board of Chiropractic Medicine requires proof of malpractice coverage or an alternative financial responsibility mechanism.
A significant legislative change took effect on July 1, 2026. Florida Senate Bill 192 removed the long-standing $1,500 limit on patient prepayments that chiropractors could accept. This means clinics can now collect larger upfront payments for treatment plans, but the new law also
imposes trust accounting requirements for those funds. If you're holding patient prepayments above the old threshold, you'll want to confirm your professional liability policy addresses potential claims related to mishandling of trust funds. This is a new exposure that many existing policies weren't written to cover.
Comparing Core Chiropractic Policies
Understanding the difference between your two primary liability policies prevents confusion when a claim hits. Too many chiropractors assume one policy covers everything, and they find out otherwise at the worst possible time.
Table: General Liability vs. Professional Liability
| Feature | General Liability | Professional Liability |
|---|---|---|
| What it covers | Bodily injury, property damage on premises | Treatment-related injuries, misdiagnosis |
| Typical claim example | Patient slips on wet floor | Patient alleges neck injury from adjustment |
| Typical limits | $1M per occurrence / $2M aggregate | $1M per occurrence / $3M aggregate |
| Covers legal defense? | Yes | Yes |
| Required by Florida? | Not mandated, but practically essential | Required for licensure (or equivalent) |
| Average annual premium | $400 - $900 | $1,500 - $4,000+ |
| Covers employee actions? | Yes, for covered events | Only if employee is a named insured |
Some carriers offer a Business Owner's Policy (BOP) that bundles general liability with property coverage at a lower combined premium. This can be a good option for solo practitioners or small clinics, but always verify that the BOP's sub-limits are adequate for your equipment value and patient volume.
Protecting Your Clinic from Modern Risks
The threats facing chiropractic clinics have expanded well beyond slip-and-fall injuries and malpractice suits. Two categories of risk deserve specific attention in 2026: cyber threats and employment-related claims.
Cyber Liability and HIPAA Compliance
Your clinic stores protected health information, and that makes you a target. Small healthcare practices are increasingly hit by ransomware attacks because hackers know these offices often lack dedicated IT security. A single breach can trigger HIPAA notification requirements, regulatory fines, and patient lawsuits.
Cyber liability insurance covers breach notification costs, credit monitoring for affected patients, forensic investigation, legal defense, and regulatory fines. Most policies also provide access to an incident response team that guides you through the first 72 hours after a breach. For a typical chiropractic clinic, cyber coverage runs $500 to $1,500 per year, a small price compared to the average healthcare data breach cost exceeding $200,000.
Make sure your policy explicitly covers ransomware payments and social engineering fraud. Some older cyber policies exclude these, and they're the two most common attack vectors hitting small medical offices.
Employment Practices Liability Insurance (EPLI)
If you have employees, you face the risk of wrongful termination, discrimination, harassment, or retaliation claims. EPLI covers legal defense and settlements for these allegations. Florida is an at-will employment state, but that doesn't protect you from claims of discriminatory firing or hostile work environment.
A former front desk coordinator who alleges they were fired for reporting sexual harassment can file a claim that costs $50,000 to defend, even if the claim has no merit. EPLI policies typically start around $800 per year for small practices. That said, your policy won't help if you don't have proper HR documentation. Keep written job descriptions, performance reviews, and termination records for every employee.
Common Questions About Chiropractic Insurance
FAQ: Coverage Limits, Costs, and Claims
How much does insurance for a Florida chiropractic clinic typically cost? Total annual premiums for a solo practitioner usually fall between $3,000 and $7,000, covering malpractice, general liability, and property. Multi-provider clinics with employees can expect $8,000 to $15,000 or more depending on revenue, claims history, and location.
Do I need separate hurricane or flood insurance? Yes. Standard commercial property policies exclude flood damage entirely and may exclude named windstorm damage depending on your county. Coastal clinics from the Panhandle to the Keys should budget for both.
What happens if I let my malpractice coverage lapse? The Florida Board of Chiropractic Medicine can suspend or revoke your license. You'll also be personally liable for any claims filed during the gap period, with no insurer to cover legal costs or settlements.
Does my policy cover telehealth visits? Most modern professional liability policies do, but some older or bare-bones policies exclude telehealth. Confirm with your carrier in writing, especially if you offer virtual consultations across county or state lines.
Should I choose claims-made or occurrence-based malpractice coverage? Occurrence policies cover any incident that happens during the policy period, regardless of when the claim is filed. Claims-made policies only cover claims filed while the policy is active. Occurrence policies cost more upfront but eliminate the need to purchase tail coverage when you retire or switch carriers.
Can I bundle my policies to save money? Yes. Many carriers that specialize in chiropractic clinic coverage offer package policies that combine general liability, property, and professional liability at a discount. Bundling can save 10-20% compared to purchasing each policy separately.
What's the most common claim against Florida chiropractors? Alleged injury from spinal manipulation, particularly cervical adjustments. The second most common involves failure to refer a patient to a specialist when symptoms indicated a condition outside the chiropractic scope of practice.
Making the Right Choice for Your Practice
Your insurance package should match the specific risks your clinic actually faces, not a generic template. A solo practitioner in Gainesville with no employees and a small lease has very different needs than a five-provider clinic in Fort Lauderdale with 20 staff members and $500,000 in equipment.
Start by auditing your current policies against the coverage types outlined above. Check for gaps in cyber liability, flood coverage, and employment practices protection, as these are the three areas where Florida chiropractors are most commonly underinsured. Review your professional liability limits and confirm every treating provider in your clinic is properly covered.
The Florida Chiropractic Association publishes regular updates on legislative changes and insurance-related developments that affect practitioners statewide. Staying current on these changes, like the SB 192 prepayment rules, helps you avoid compliance surprises.
Work with a broker who understands healthcare practices in Florida specifically. A generalist agent selling you the same BOP they'd write for a retail store won't catch the coverage gaps that matter most to your clinic. Ask potential brokers how many chiropractic clients they serve and whether they can explain your state's financial responsibility requirements without looking them up. The right broker pays for themselves by preventing the one uncovered claim that could otherwise shut your doors.
ABOUT THE AUTHOR:
MONTREAL MORAND
With over 20 years of leadership experience in the insurance industry, I’ve dedicated my career to helping clients and agents make informed, confident decisions about their coverage. I’ve led high-performing teams, managed more than $128 million in premium, and earned multiple national awards for excellence. Today, my mission remains the same — to educate, empower, and provide dependable protection for the communities we serve.
Contact Us
Protect the Things That Matter Most
Reliable Coverage for Your Home & Lifestyle
Home Insurance
Protect your home, belongings, and personal liability with reliable coverage.
Stronger Coverage for Your Operations
Essential Protection for Your Company
Coverage built for businesses that depend on people, property, and equipment.
Industries We Support
Insurance for Everyday Local Businesses
Simple, reliable protection for the people who keep our communities running.
Plumbers
Plumbers Insurance
Protection for job-site hazards, tools, and customer property.
Restaurants
Restaurants Insurance
Coverage for fire risks, food inventory, and general liability.
HVAC Contractors
HVAC Contractors Insurance
Insurance for service vehicles, equipment, and installation risks.
Frequently Asked Questions
Helpful Answers to Common Questions
Quick guidance to help you understand your coverage.
What types of insurance does Macpherson Insurance Agency offer?
We provide both personal and commercial insurance solutions. On the personal side: homeowners, automobile, condo, renters, windstorm, flood, excess flood, and more. On the commercial side: general liability, property, inland marine, ocean marine, workers compensation, and more.
Do you specialize in homeowners insurance in South Florida?
Yes. We specialize in homeowners coverage in South Florida and work with multiple carriers based on your property’s age, location and replacement cost.
What does “replacement cost” mean in a policy?
Replacement cost is the cost to rebuild your home to the same standard it had before a loss — not the market value of your property.
Why is it important that my insurer is licensed in Florida?
Licensed Florida insurers are continuously monitored for financial stability — if one fails, the Florida Insurance Guaranty Fund may reimburse insureds for unpaid claims up to a limit.
Can I lower my homeowners premium with discounts?
Yes — mitigation features like impact glass, storm shutters, roof straps, and approved sheathing may qualify you for significant credit reductions.
Do you offer payment plans or premium financing?
Yes. In many cases, payment plans and premium financing are available to make coverage more affordable and manageable over time.
From the Blog
Helpful Tips & Insurance Guidance
Articles created to make insurance easier to understand.


Contact Us
Phone
Location