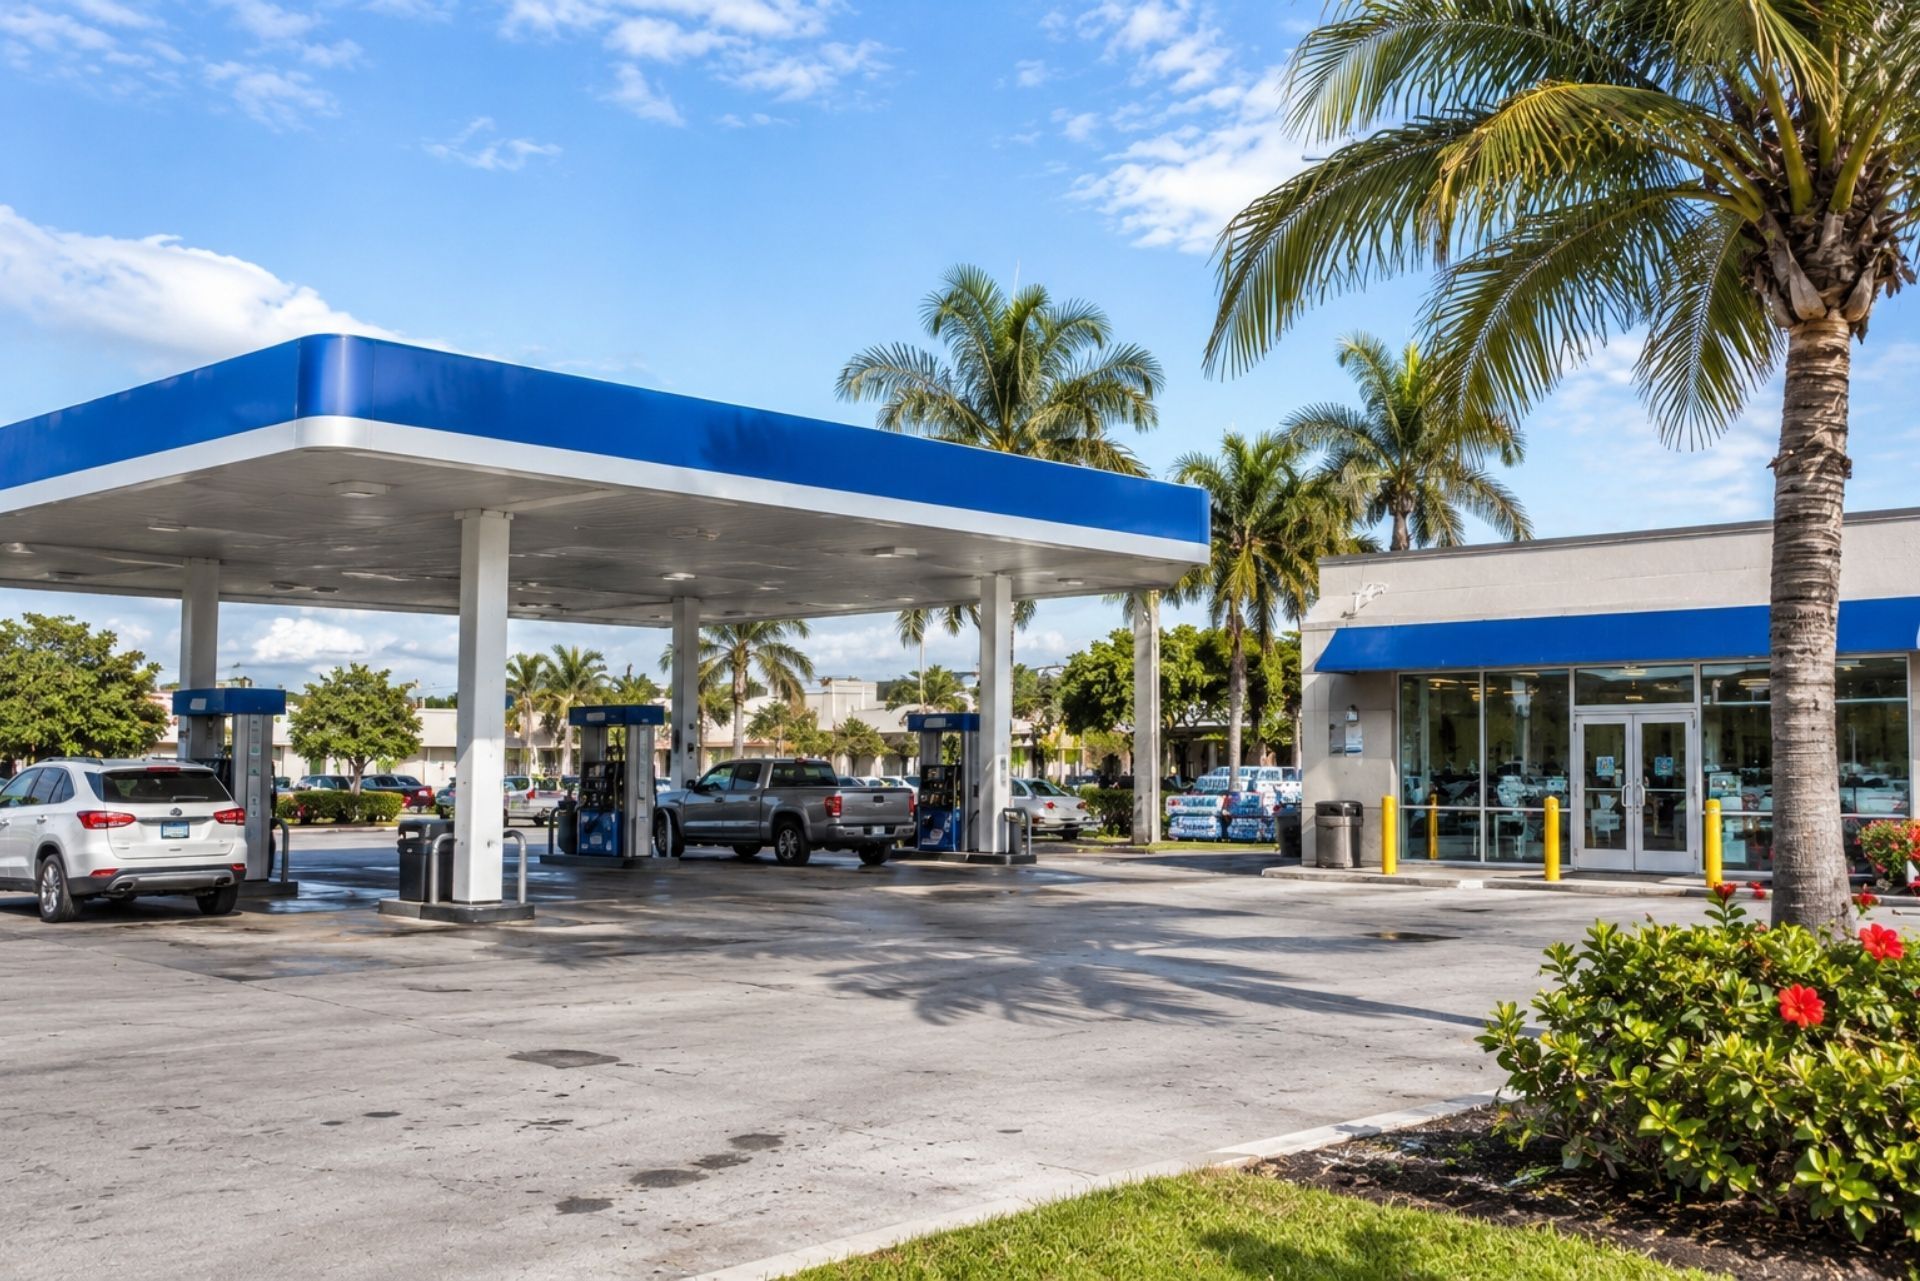
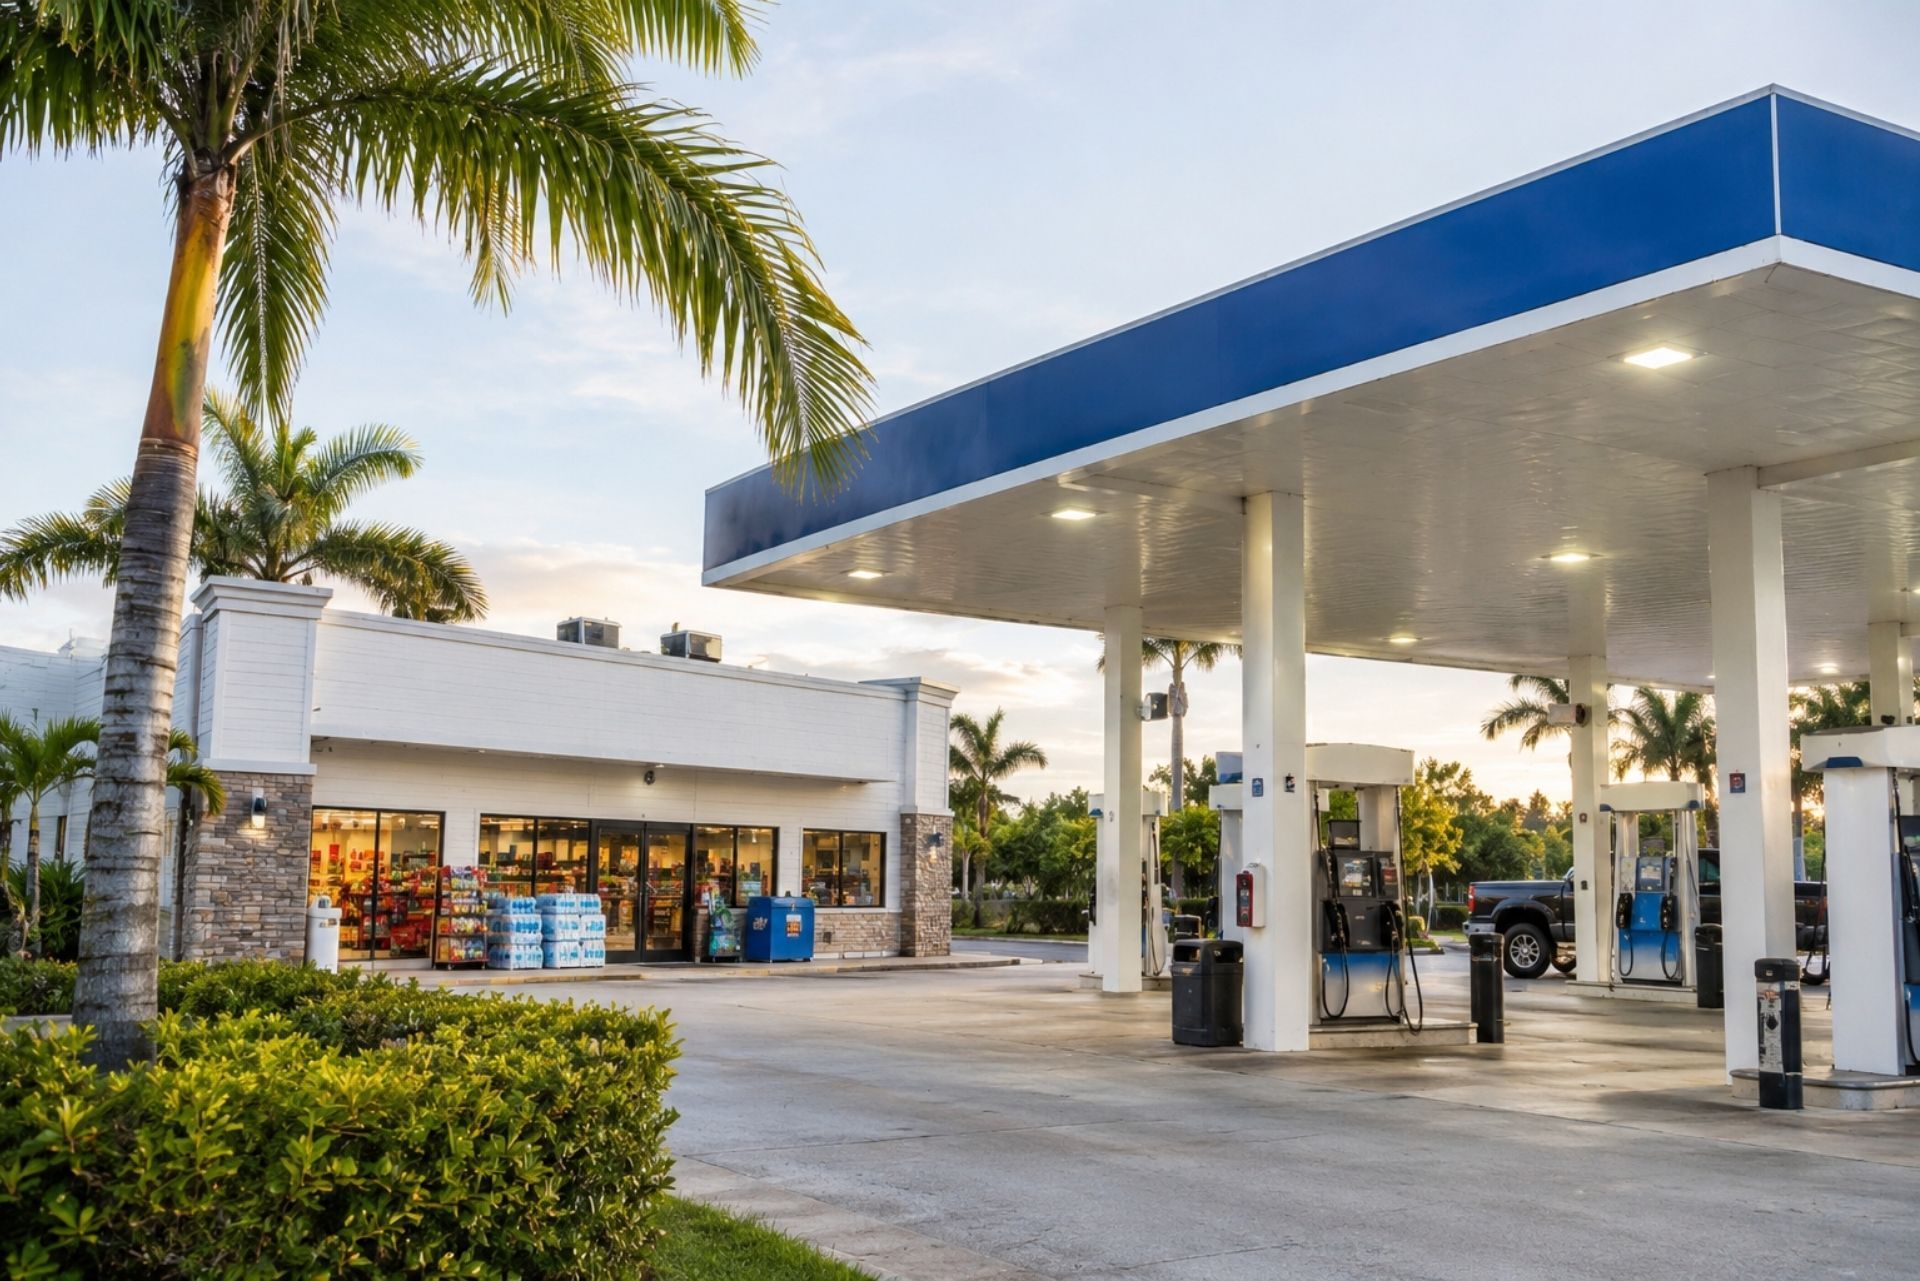
Picture a Tuesday night in Kissimmee. A customer slips on a diesel slick near pump four, a skimmer turns up inside your dispenser the next morning, and your inspector flags a corroded line near your underground tank the same week. None of those events is rare for a Florida fuel retailer. Each one hits a different part of your insurance program.
Most station owners buy coverage in pieces, one policy at a time, usually when a lender or landlord demands it. That's where operators get caught. A convenience store policy written for a strip-mall shop won't cut it when you're storing thousands of gallons of gasoline under the parking lot and selling lottery tickets at 2 a.m.
This guide covers gas station insurance in Florida from the ground up:
general liability, property, pollution and tank liability, crime, workers' compensation, and what you can expect to pay. It's written for owners and operators who want to understand what each policy actually does, where the gaps hide, and how to build a program that holds up when the claim arrives. You'll also find real monthly premium figures, a coverage comparison table, and a practical checklist you can use at your next renewal.
The Risk Landscape for Florida Gas Station Owners
Florida stacks risks on fuel retailers that owners in Ohio or Arizona never think about. Hurricane season runs six months. Saltwater air near Fort Lauderdale, Tampa Bay, and the Keys corrodes canopies, dispensers, and tank fittings faster than inland stations see. A high water table across much of South Florida means a small fuel leak can reach groundwater quickly, which raises cleanup costs.
The state also regulates convenience operations closely. Under the Florida Convenience Business Security Act, stations with convenience operations must keep lighted parking at a minimum of 2 foot-candles per square foot measured 18 inches above the surface. That's a compliance issue, sure. It's also a liability issue, because a plaintiff's attorney in a parking-lot robbery case will check your lighting first.
Then there's the pump itself. Florida law now requires stations to use
secondary security measures beyond simple tamper tape to stop card skimming, and to report breaches to FDACS within 90 days. Here's what that means for you : your exposure covers customers, fuel, cash, data, and weather, all at one address.
By: Montreal Morand
Founder & Managing Partner
Macpherson Insurance Agency
Core Coverages: General Liability and Commercial Property
General liability is your first line of defense against third-party claims. It pays for bodily injury and property damage you cause to others, plus legal defense. Typical gas station GL claims include slip-and-falls on oil-stained concrete, a customer tripping over a hose, or a car damaged by a malfunctioning car wash arm. GL also usually includes products liability, which matters if you sell food or if someone claims contaminated fuel damaged their engine.
One thing to keep in mind : standard GL policies exclude pollution almost entirely. If fuel spills and seeps into a neighbor's property, your GL carrier will likely deny it. That's why pollution coverage sits in its own section below.
Commercial property insurance covers your building, canopy, pumps, coolers, inventory, and signage. For Florida stations, read three things closely:
- Windstorm deductibles : Often a percentage of insured value, not a flat dollar amount. A 5% deductible on a $1.5M building means $75,000 out of pocket.
- Equipment breakdown : Covers compressors, walk-in coolers, and dispenser electronics after power surges.
- Business income : Replaces lost revenue when a storm closes you for weeks. Check the waiting period.
Many smaller operators bundle GL and property in a
Business Owner's Policy, though high-volume or 24-hour stations often need standalone forms.
Protecting Your Assets from Environmental and Crime Risks
Environmental and crime losses tend to be the most expensive claims a station faces, and they're the ones least likely to be covered by a standard package policy. Treat both as separate purchases.
Pollution and Storage Tank Liability
Underground and aboveground storage tanks carry federal and state financial responsibility requirements, and storage tank liability insurance is the most common way owners meet them. These policies cover cleanup of contamination from your tanks, third-party bodily injury and property damage, and legal defense tied to a release.
Here's a real-world scenario. A pinhole leak in a fiberglass line goes undetected for months at a station in Hialeah. By the time monitoring catches it, the plume has moved under an adjacent laundromat. You're looking at soil excavation, groundwater monitoring wells, and a property damage claim from the neighbor. That's a tank liability claim, not a GL claim.
The catch is that most tank policies are written on a claims-made basis. If you switch carriers without securing prior acts coverage, a leak that started under the old policy may fall through the cracks. Also confirm whether the policy covers spills at the dispenser and during fuel deliveries, not just from the tank itself.
Crime and Employee Dishonesty Insurance
Gas stations handle cash around the clock, and that invites both outside theft and inside jobs. Crime coverage typically includes employee dishonesty, money and securities theft on and off premises, robbery, forgery, and computer fraud.
Employee theft is the claim owners underestimate most. A clerk voiding lottery sales or skimming the register in small amounts can drain thousands over a year before anyone notices. Your property policy won't touch it.
Florida's skimmer rules add another layer. If a breach exposes customer card data, you may face notification costs and claims that call for a cyber liability endorsement. Crime insurers will also look at your camera setup, since state law requires a security camera system that can record and retrieve images to help identify offenders. A working system helps both your compliance and your underwriting.
Florida Workers' Compensation and Employment Rules
Florida requires most non-construction businesses with four or more employees, full-time or part-time, to carry workers' compensation. Most gas stations hit that threshold quickly once you staff three shifts. Corporate officers can file exemptions in some cases, but those officers then go without coverage themselves.
Station employees face real injury risks. Common claims include back strains from stocking coolers and lifting cases of drinks, cuts from box cutters, burns from hot food equipment, and slips on wet floors. The biggest exposure is violence. Night clerks injured during robberies generate some of the most severe workers' comp claims in convenience retail, often involving surgery and long-term disability.
Payroll drives your premium, along with your classification code and experience modification rate. Misclassifying employees is a common mistake. If a worker spends real time on car wash maintenance or fuel handling, an auditor may reclassify them at year end, and you'll owe the difference.
This matters because the state penalizes noncompliance hard, with stop-work orders and fines. A documented safety program, robbery prevention training, and drop safes can help keep both claims and premiums down.
Not every station needs the same program. A single-pump rural stop near Ocala has different exposures than a 24-hour travel plaza off I-95 in Jacksonville. The table below shows how basic and extended setups typically differ.
| Coverage | Basic Program | Extended Program |
|---|---|---|
| General Liability | $1M per occurrence / $2M aggregate | $1M/$2M plus $5M umbrella |
| Property | Building and inventory | Adds equipment breakdown, signs, business income |
| Pollution / Tank | Minimum to meet financial responsibility | Higher limits, delivery and dispenser spills |
| Crime | Employee dishonesty only | Adds robbery, money off-premises, computer fraud |
| Workers' Comp | Statutory coverage | Statutory plus higher employer's liability limits |
| Cyber | Not included | Card breach and notification costs |
That said, limits should follow your actual exposure. Stations near schools, busy intersections, or tourist corridors in Orlando often justify an umbrella, since a single serious auto or premises injury can blow past $1M. Lenders and franchise agreements frequently set minimums too, so pull those contracts before you choose limits.
What Influences Gas Station Insurance Costs in Florida?
Real numbers help here. Typical monthly costs for Florida gas stations run about $85 for general liability and $100 for pollution liability, with a Business Owner's Policy starting around a $100 monthly base. Those are starting points. Your quote can land well above them.
The factors that move your premium most:
- Location : Coastal counties and high-crime ZIP codes cost more for property and crime.
- Tank age and construction : Older single-walled steel tanks cost far more to insure than double-walled fiberglass with leak detection.
- Hours : 24-hour operations raise crime and workers' comp exposure.
- Add-ons : Car washes, hot food, and repair bays each bring their own risks.
- Claims history : Prior spills or robberies follow you for years.
- Payroll : The main driver of workers' comp pricing.
The Florida property market has eased somewhat. The state-backed insurer of last resort reported an average 8.8% statewide rate decrease for multiperil policies in 2026, and its policy count fell to roughly 255,000 by late September 2026 as private carriers returned. More carrier competition gives you better odds of finding a fair property quote, so shop at renewal.
Common Questions About Insuring a Florida Gas Station
Does my general liability policy cover a fuel spill? Usually not. Most GL policies exclude pollution, so you need a separate pollution or storage tank liability policy.
Do I need workers' comp if I only have part-time clerks? Probably. Florida counts part-time workers toward the four-employee threshold for non-construction businesses.
What happens if a skimmer is found on my pump? You must report the breach to FDACS within 90 days. A cyber endorsement can help cover notification and related costs.
Is a Business Owner's Policy enough for my station? It can work for smaller stations, but it won't include pollution, workers' comp, or full crime coverage. Most owners need additional policies.
Will older tanks raise my premium? Yes. Insurers price tank coverage heavily on age, construction material, and leak detection, and some won't write very old single-walled tanks at all.
Can I lower my rates?
Upgraded tanks, working cameras, good lighting, drop safes, and a clean claims history all help.
Making the Right Choice for Your Station
A well-built program for a Florida fuel retailer treats each exposure separately : premises injuries under GL, buildings and storms under property, leaks under tank liability, theft under crime, and staff injuries under workers' comp. The expensive mistakes happen in the gaps between them, like assuming GL covers a spill or letting claims-made tank coverage lapse during a carrier switch.
Before your next renewal, run this quick audit:
- Confirm your tank policy's retroactive date and whether it covers delivery spills.
- Check your windstorm deductible in actual dollars.
- Verify lighting and camera compliance with state security rules.
- Review employee classifications against what staff actually do.
- Make sure your crime policy covers employee dishonesty and robbery.
- Ask whether a cyber endorsement covers skimming breaches.
Find out where your coverage stops now, while it's cheap to fix. Learning it after a storm or a spill is too late.
ABOUT THE AUTHOR:
MONTREAL MORAND
With over 20 years of leadership experience in the insurance industry, I’ve dedicated my career to helping clients and agents make informed, confident decisions about their coverage. I’ve led high-performing teams, managed more than $128 million in premium, and earned multiple national awards for excellence. Today, my mission remains the same — to educate, empower, and provide dependable protection for the communities we serve.
Contact Us
Protect the Things That Matter Most
Reliable Coverage for Your Home & Lifestyle
Home Insurance
Protect your home, belongings, and personal liability with reliable coverage.
Stronger Coverage for Your Operations
Essential Protection for Your Company
Coverage built for businesses that depend on people, property, and equipment.
Industries We Support
Insurance for Everyday Local Businesses
Simple, reliable protection for the people who keep our communities running.
Plumbers
Plumbers Insurance
Protection for job-site hazards, tools, and customer property.
Restaurants
Restaurants Insurance
Coverage for fire risks, food inventory, and general liability.
HVAC Contractors
HVAC Contractors Insurance
Insurance for service vehicles, equipment, and installation risks.
Frequently Asked Questions
Helpful Answers to Common Questions
Quick guidance to help you understand your coverage.
What types of insurance does Macpherson Insurance Agency offer?
We provide both personal and commercial insurance solutions. On the personal side: homeowners, automobile, condo, renters, windstorm, flood, excess flood, and more. On the commercial side: general liability, property, inland marine, ocean marine, workers compensation, and more.
Do you specialize in homeowners insurance in South Florida?
Yes. We specialize in homeowners coverage in South Florida and work with multiple carriers based on your property’s age, location and replacement cost.
What does “replacement cost” mean in a policy?
Replacement cost is the cost to rebuild your home to the same standard it had before a loss — not the market value of your property.
Why is it important that my insurer is licensed in Florida?
Licensed Florida insurers are continuously monitored for financial stability — if one fails, the Florida Insurance Guaranty Fund may reimburse insureds for unpaid claims up to a limit.
Can I lower my homeowners premium with discounts?
Yes — mitigation features like impact glass, storm shutters, roof straps, and approved sheathing may qualify you for significant credit reductions.
Do you offer payment plans or premium financing?
Yes. In many cases, payment plans and premium financing are available to make coverage more affordable and manageable over time.
From the Blog
Helpful Tips & Insurance Guidance
Articles created to make insurance easier to understand.


Contact Us
Phone
Location